

Vertical Aerospace just pointed to a genuine engineering win and reopened its order book, and in the same breath told investors its funding problem was solved. The numbers that landed beside that celebration do not survive the subtraction. Here is the door.
As of August 13, the company held about $134 million of cash, expected to rise to roughly $148 million on a pro forma basis once its new financing package arrived. Against that balance sits management's own projection of about $150 million of net cash outflows over the next 12 months. Call the arithmetic: the "financing secured" figure and the projected burn cancel each other out. The package does not fund the program. It funds roughly the next year.
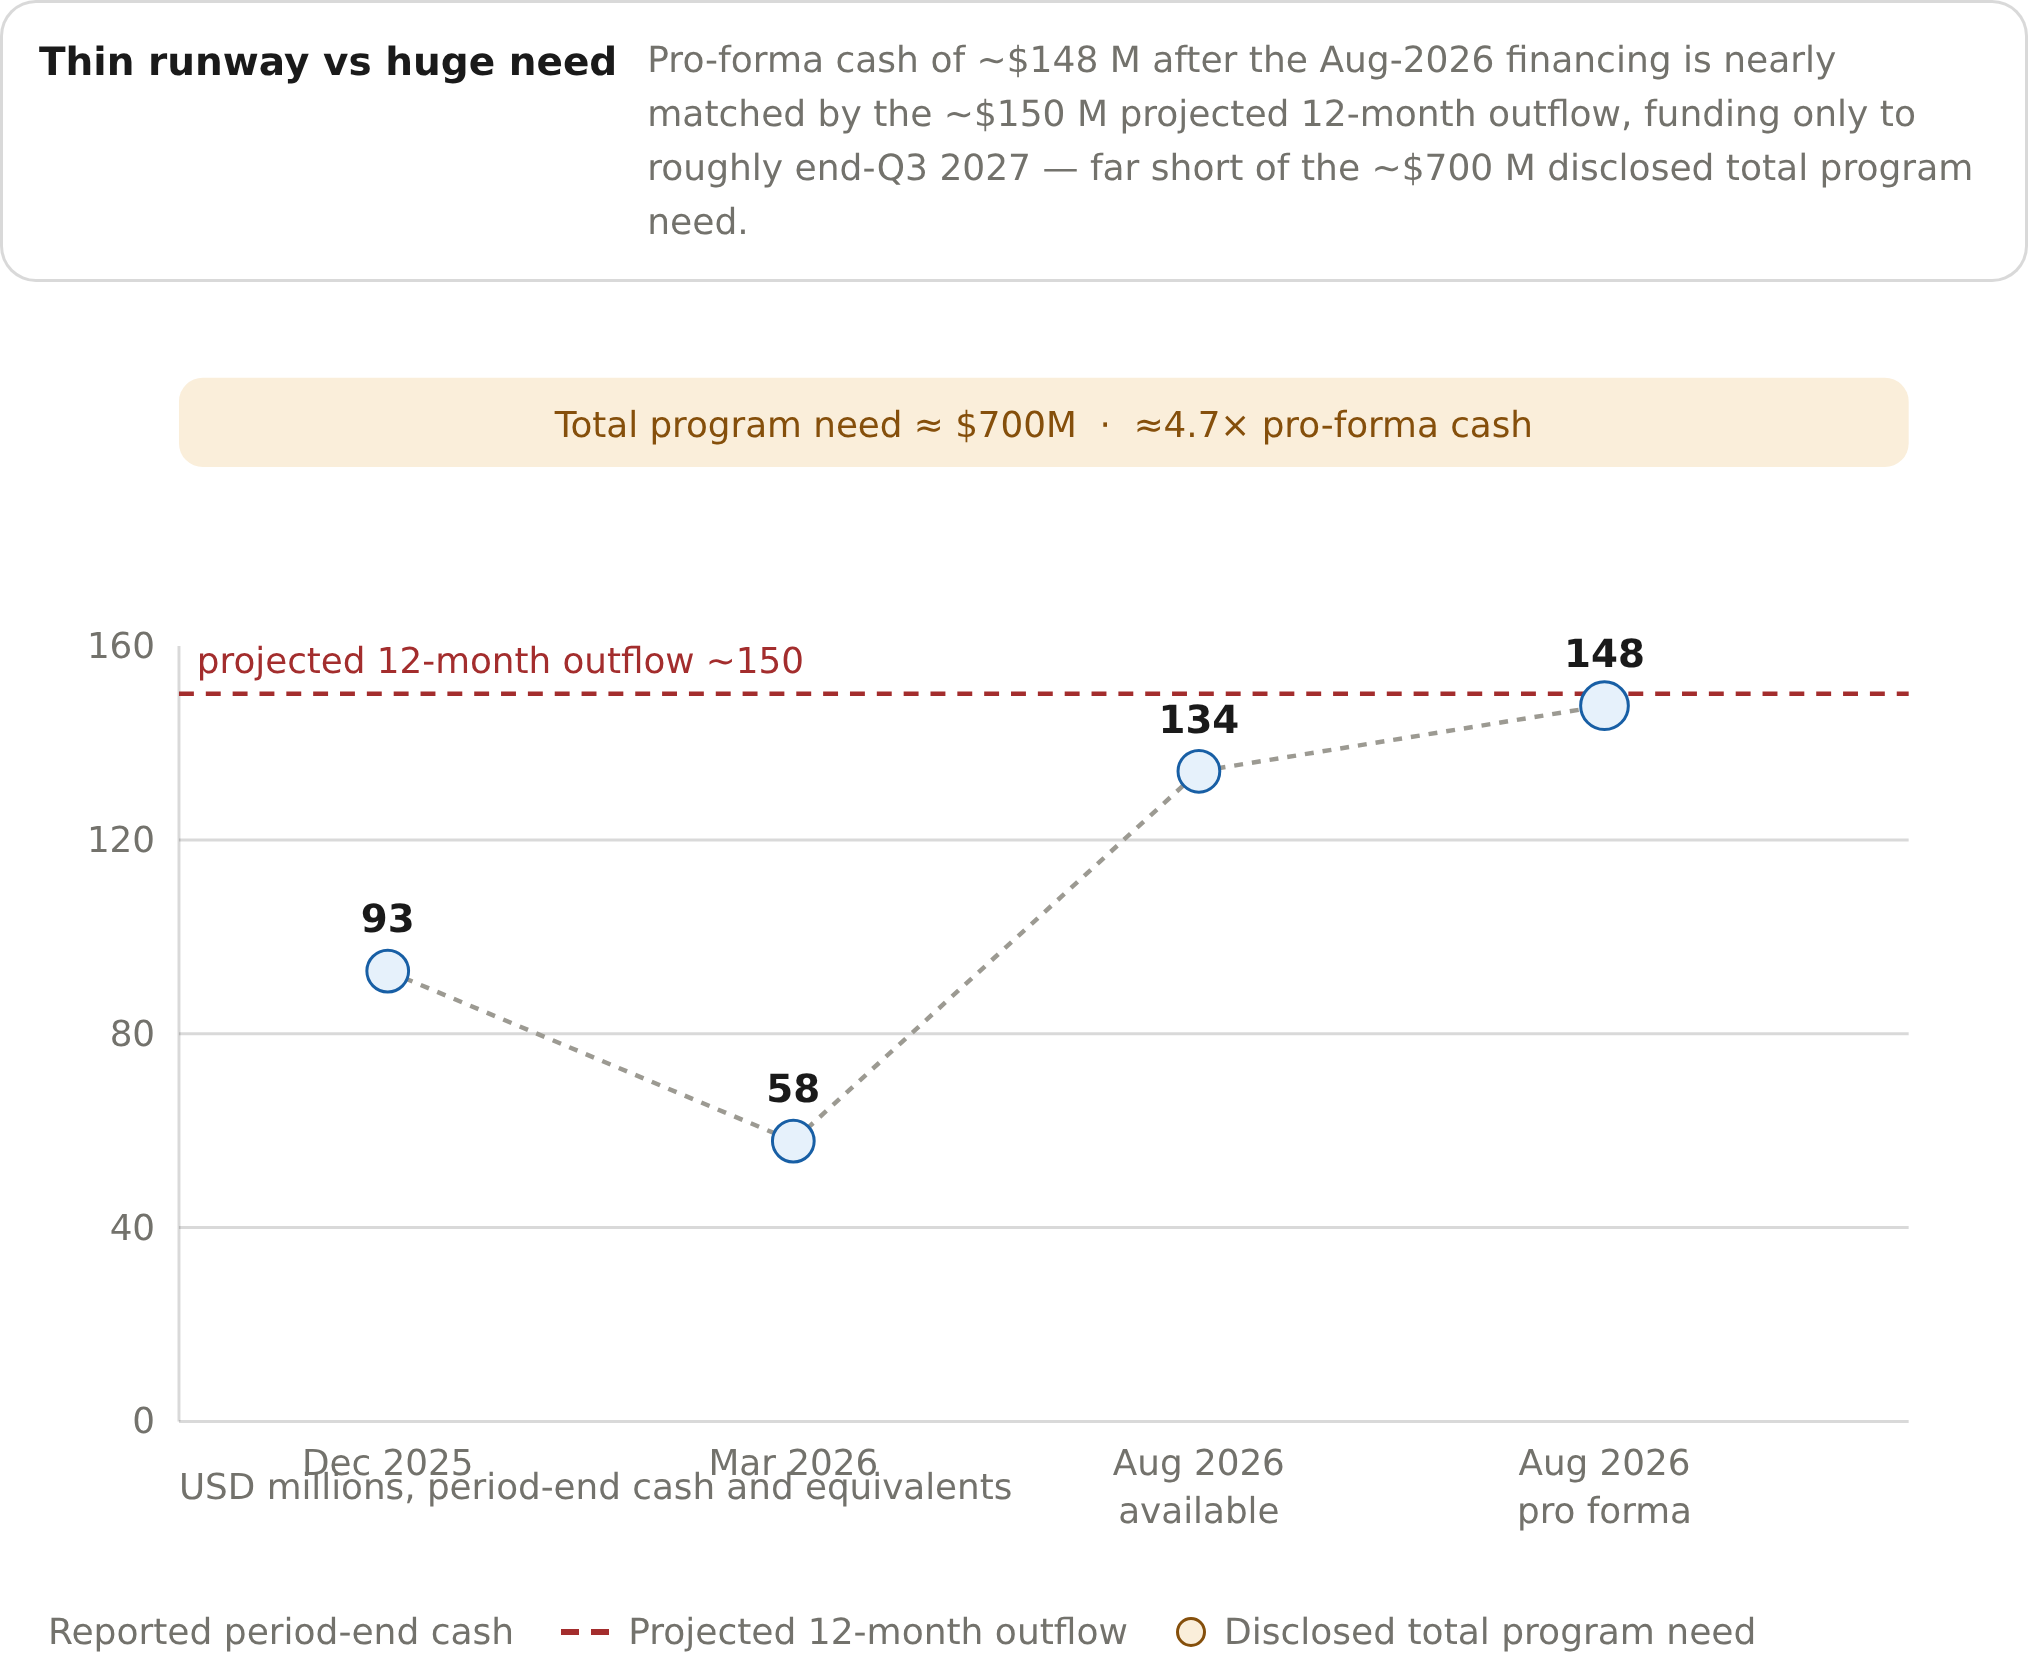
| Reported date | Cash and equivalents (USD m) | Note |
|---|---|---|
| 2025-12-31 | 93 | base; alternate source reports ~69 |
| 2026-03 | 58 | per March 2026 report |
| 2026-08-13 (available) | 134 | available cash |
| 2026-08-13 (pro forma) | 148 | pro forma after financing |
The filing reinforces the point in two currencies. On the cash-flow statement, the company consumed about $112 million of net operating cash in the first half of 2026, spending on flight testing, certification prep, supplier payments, and battery development. On the income statement the same half produced an operating loss of roughly £75.8 million. Neither line is a commercial sale; VerticalEVTL-- remains pre-revenue.
That is why the runway figure matters. The company says the added cash stretches it through roughly the end of the third quarter of 2027. A pre-revenue developer reaching certification on a year-and-change of runway is a short lane — and the year of runway is not the program's cost.
Now widen to the full bill. On the same update, management put the total cash need for the program at around $700 million. Set the ~$148 million on hand against that and you finance roughly a fifth of the disclosed total. Subtract and the residual sits on the order of $550 million. That number is derived, not printed by the company, and its exact size depends on reading the $700 million as a cumulative total against current cash rather than a remaining amount — the sensible reading of "total cash need," but worth pinning down before you lean on it. Every reconciliation still leaves more than half a billion dollars for a program whose financing management framed as secured.
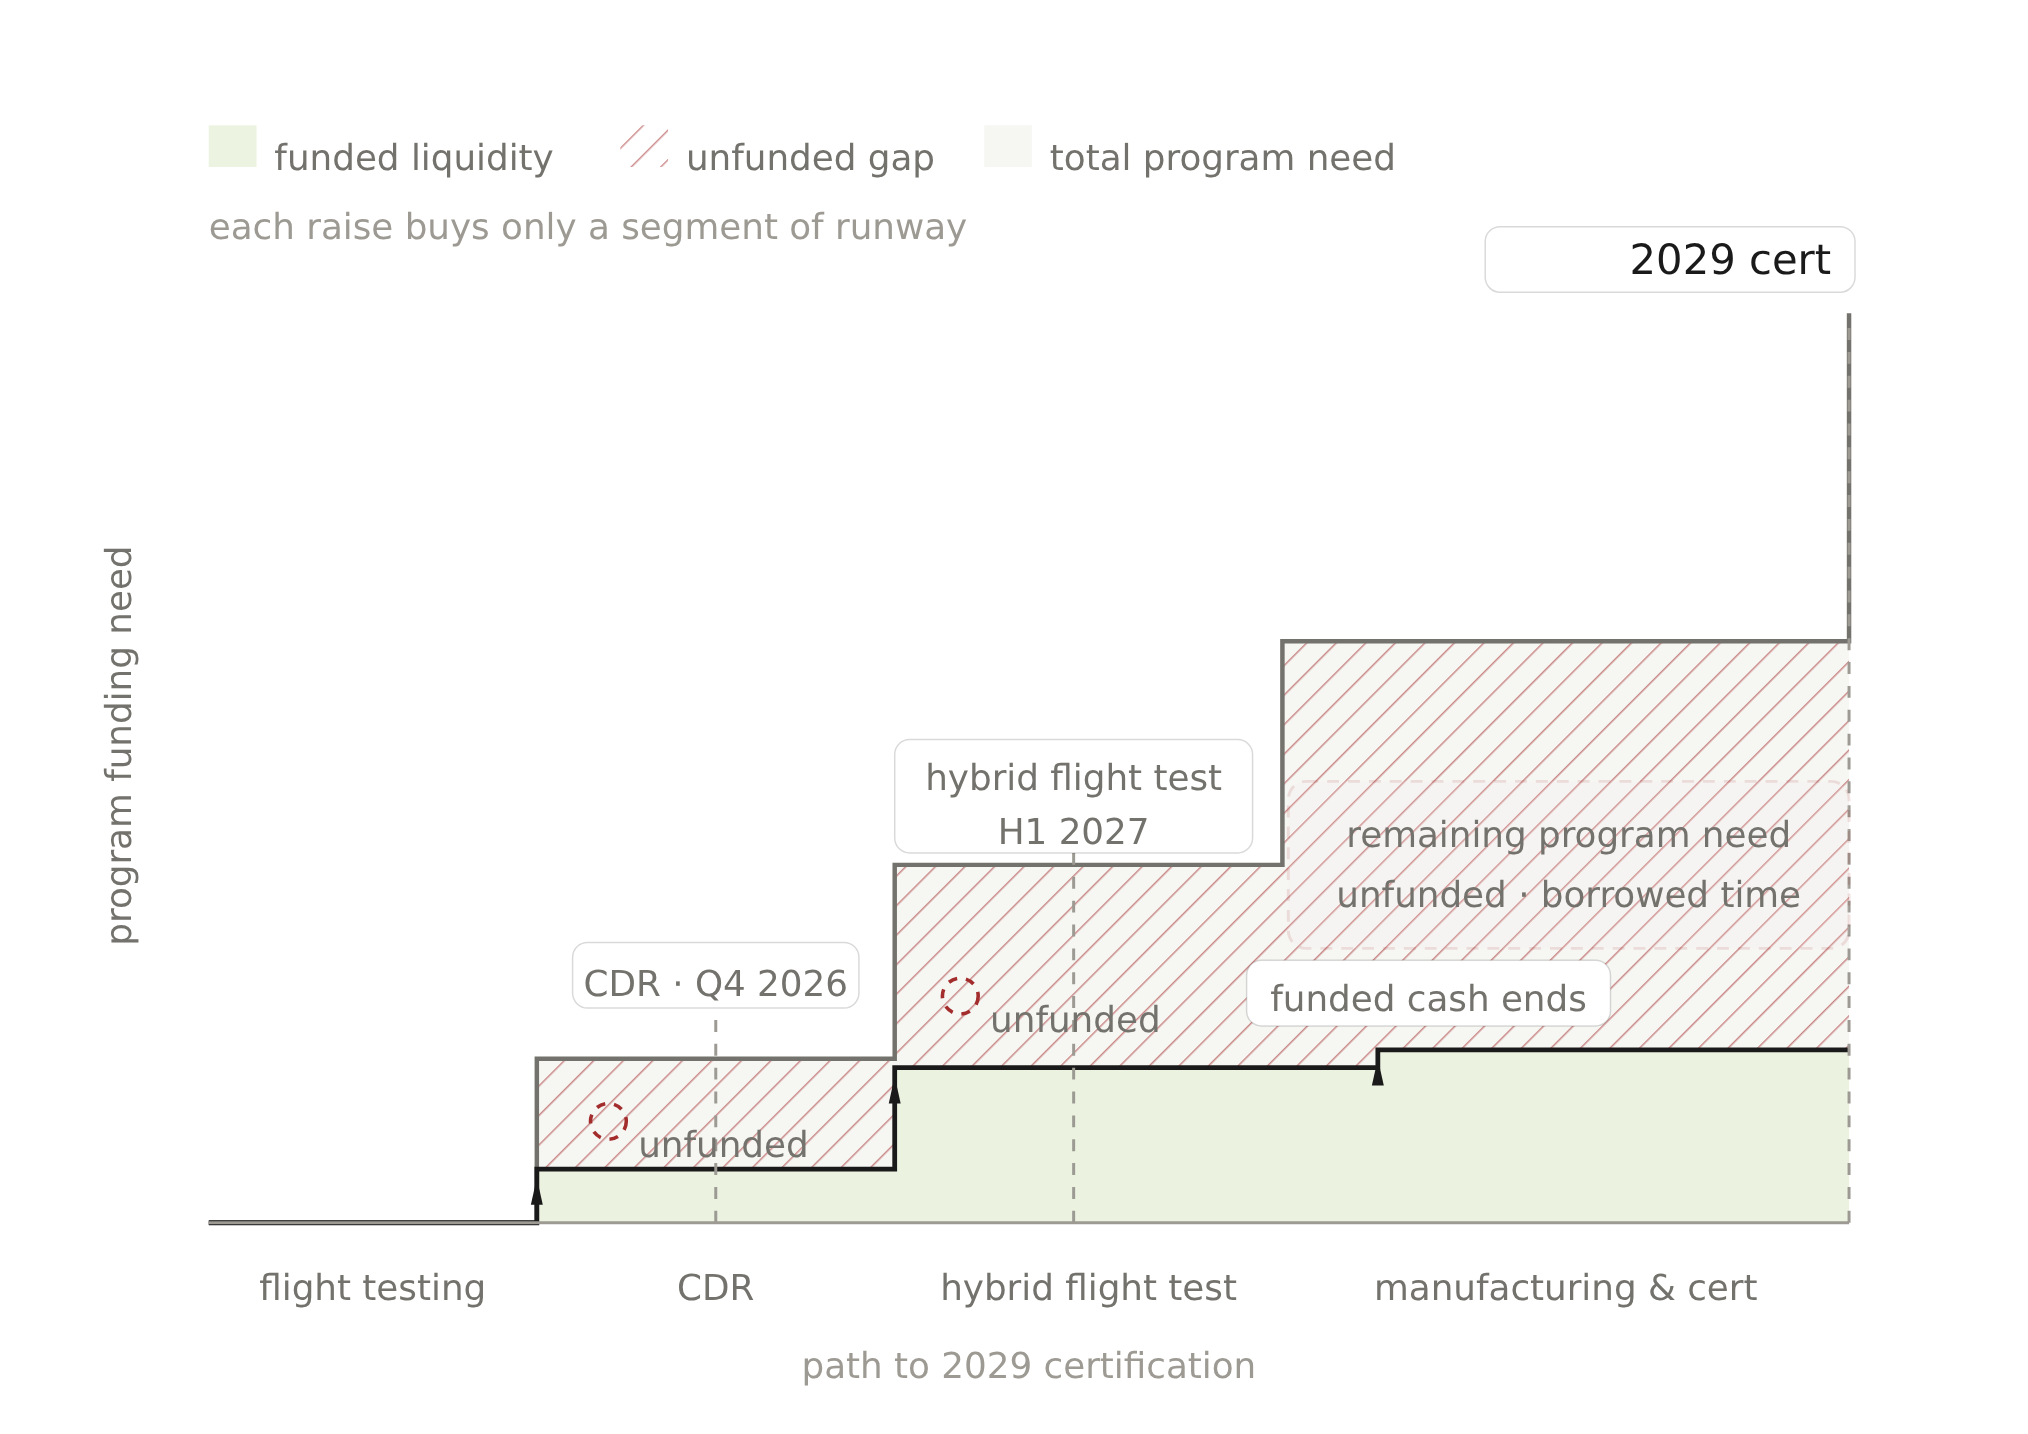
The program also became costlier at the same time. Vertical moved its type-certification target out of 2028 and into 2029, a year that buys flight-test hours, certification work, and cash the funding does not yet cover. The gates directly ahead — completion of the aircraft-level Critical Design Review in Q4 2026 and the start of hybrid-electric flight testing in H1 2027 — are where a slip would push the bill higher still.
Do not overstate the consolation in the word "secured." A meaningful slice of the package is conditional, equity-linked paper: a $40 million accelerated drawdown under Mudrick Capital's convertible-note facility and a $25 million drawdown under a Yorkville preferred-equity facility, alongside $35 million of underwritten equity. Management calls roughly $700 million of remaining Yorkville facility capacity committed capital subject to conditions, limitations, and market environment. That is language for money not in the bank today, and money that, when drawn, converts into equity and dilutes the holders paying for it. This is not an accounting oddity hiding in a footnote; it is a company buying time with paper whose true price shows up later in the share count.
Verdict: Vertical is not out of money. It is funded to the end of Q3 2027 and no closer to a certification. The celebrated milestone is real; the financing covers about one year out of a disclosed $700 million commitment, leaving on the order of half a billion dollars still to be raised through capital that will cost existing holders in dilution. The settling events are already on the calendar: reported period-end cash against that ~$150 million projected outflow, the Q4 2026 critical design review, and whether or when the conditional Yorkville capacity has to be drawn under an unfavorable market. Watch those, and the width of the gap will confirm itself before the stock's story fully does.









Comments
No comments yet