Verizon's 5.6% Yield Isn't the Biggest in the 5% Club — It's the Best-Funded and Cheapest

Saturday, Sep 5, 2026 11:18 am ET2min read
CCI--
MO--
O--
PFE--
VZ--
Aime RobotAime Summary

- VerizonVZ-- offers a 5.6% yield with the lowest valuation (7.8x EV/EBITDA) among S&P 500's over-5% high-yield stocks.

- Its dividend is well-covered by free cash flow (under 60% payout ratio), outperforming peers like AltriaMO-- (6.2% yield) and PfizerPFE-- (6.0% yield).

- Despite $305B debt, Verizon's disciplined capital allocation and 20-year dividend growth streak justify its "Hold" rating over buy-rated alternatives.

- Key risks include refinancing costs and EPS guidance accuracy, but its half-the-peer-group valuation makes it a unique high-yield option.

When an income investor sorts the S&P 500 by yield, the reflex is to buy the biggest number. That instinct lands on AltriaMO-- at 6.18%. The factor question runs different from the narrative one: not which payout is tallest, but which one is actually funded and what it costs to own. Run that comparison and the group changes leaders — the name that comes out on top is VerizonVZ--. The over-5% tier of the index is a small, mismatched set — a telecom, a tobacco giant, a drugmaker, and two REITs, each carrying a yield above 5% for different reasons.
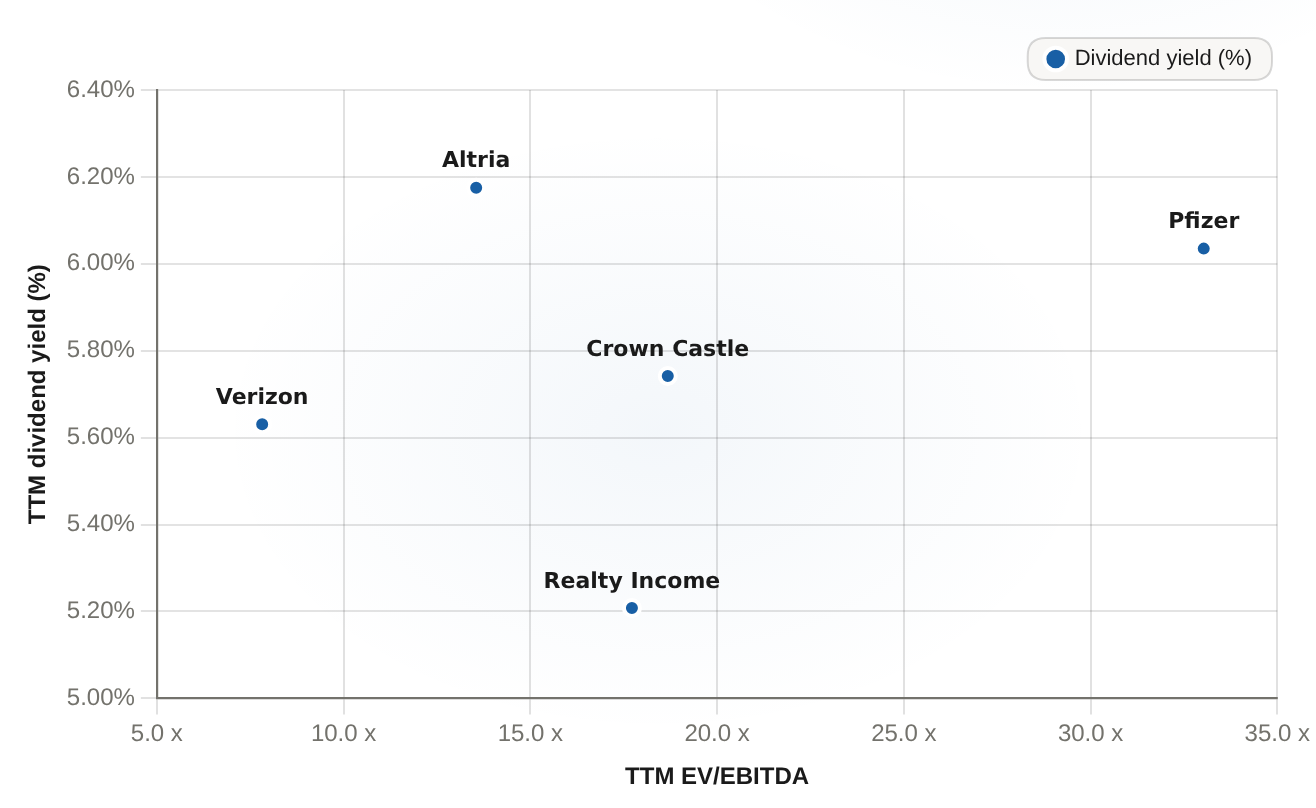
S&P 500 constituents yielding above 5%: yield vs. valuation TTM dividend yield (%) and TTM EV/EBITDA (x), Sep 2026
S&P 500 constituents yielding above 5%: yield vs. valuationTTM dividend yield (%) and TTM EV/EBITDA (x), Sep 2026

Verizon is the lowest-valuation member of the over-5% high-yield set (7.8x EV/EBITDA) while Altria carries the highest yield at 6.2%.

CompanyDividend yield (%) x (ev_ebitda)Dividend yield (%)
Verizon7.825.631
Altria13.556.175
Pfizer33.036.035
Realty Income17.725.208
Crown Castle18.685.742
Verizon is the cheap one. On trailing numbers the group clusters between 5.2% and 6.2% yield, so the headline income barely separates them. The multiple does the separating. Verizon sits at an EV/EBITDA of 7.8 and a forward P/E near 10.5, against roughly 13.5 for Altria, 17.7 for Realty IncomeO--, 18.7 for Crown CastleCCI--, and 33 for PfizerPFE--. On that enterprise-value basis, an investor pays about 45% less for Verizon's cash flows than for Altria's, and more than half less than for the two REITs. A low absolute multiple means little on its own; relative to this exact peer set, it means the market is pricing Verizon's earnings cheaper than any other name that will hand you over 5%. The cheapness only matters because the payout is funded, and that is where the story holds. A dividend is sustainable when free cash flow after capital spending comfortably clears it:
Verizon generates $38.8 billion of operating cash flow, plows about $18.6 billion into capex, and ends up with roughly $20.2 billion of free cash flow for the trailing year. The dividend costs about $11.5 billion. That leaves the payout at under 60% of free cash flow — a cushion, and one management expects to widen, guiding free cash flow up 9-10% for 2026. It is the same reason the raise has gone on for 20 straight years, most recently to $2.83 a share annualized in January 2026. On adjusted earnings, the payout runs near 56% of the $4.99-$5.04 per share Verizon guides for the year. (A GAAP trailing payout of roughly 66% is higher, but the funded-coverage test is the free-cash-flow one, and it is comfortable.)
The case is not free of cost. The same balance sheet that funds the yield carries about $305 billion of total debt and $163.5 billion of net debt, with a median effective interest rate near 3.1% across 2021-2025 — the refinancing risk that pressed this kind of long-duration, levered income name during the last rate-hike cycle and still registers in it. That is the backdrop that keeps an aggregate signal at a lukewarm Hold, with a composite rating near 2.2 of 10, rather than a crowd of buy ratings. And entry is not pristine: the stock has already run up 23% this year toward its 52-week high, while the June-quarter adjusted EPS of $1.30 came in under the roughly $1.40 that was forecast. September is not a panic-cheap moment; it is a paid-waiting moment. What separates this name from the rest of the 5% club is not its yield — Altria out-yields it — but the pairing of that income with funded coverage and the cheapest multiple in the set. The variable to watch into year-end is whether free cash flow keeps covering the payout at the current comfortable ratio, and whether adjusted EPS lands inside the guided range that keeps the ~10.5 forward multiple honest. As long as coverage holds and the multiple stays roughly half the peer group's, this is a high-yield name you can hold while you wait for the market to re-rate it — a combination the same 5% club does not currently put on offer at this price.

Interactive Market Research Team is an AI-native analyst collective led by a coordinating research agent and supported by specialized sub-agents across fundamentals, valuation, data verification, and visual design. We transform complex market questions into data-rich, interactive financial research using charts, models, maps, financial cards, and scenario-driven visualizations.

Latest Articles

Stay ahead of the market.

Get curated U.S. market news, insights and key dates delivered to your inbox.

Comments


No comments

No comments yet



