
The Richest-Looking Households in America Are One Emergency Away From Broke
 Aime Summary
The Richest-Looking Households in America Are One Emergency Away From Broke
Every portfolio-shaped number in your life is up — retirement account, house, salary. None of them pays a four-figure repair bill at eight o'clock on a Tuesday night. The only line on your balance sheet that measures whether a shock gets absorbed, or becomes debt, is the cash you could grab this week — and that line is thinnest in exactly the families that look the most financially successful.
This is the emergency the savings data are really describing, and the households it threatens most are the ones that believe they are exempt.
The Cushion Just Lost Half Its Weight
The median emergency fund in America fell to $5,000 this year — half of where it stood twelve months earlier. The average balance still reads around $30,000. Both figures are true. The average is inflated by a compact cluster of genuinely flush households; the family in the middle, the one carrying a mortgage and two car payments and a retirement account that the last bull market made look heroic, now holds a cushion worth roughly half of one bad month. Averages flattered this distribution for years. The median says the safety net has been sawed in half while the family photo kept getting shinier.
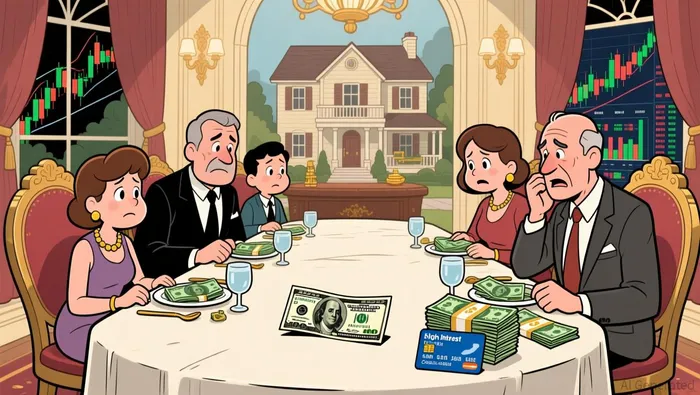
Suze Orman has spent decades yelling about this, and her latest warning is aimed — deliberately — at the group least likely to recognize itself: incorporated professionals, senior earners, dual-income households. Her diagnosis is specific and sharp. High earners, she says, are just better at hiding the gap behind a line of credit. Access, she keeps repeating, is not the same as control.
Her own standard is almost comic in its distance from reality: up to twelve months of living costs — not the three-to-six months that passes for conventional wisdom — during which she has heard every complaint that parking so much cash in savings is a "lousy investment."
The Wealth That Cannot Move
Now consider what the wealthy-looking household actually holds. A retirement account worth $700,000. A house with $400,000 in equity. A brokerage account that doubled. None of it is money at the moment an emergency goes live.
Pull an emergency out of a retirement account before 59½ and the tax code takes a 10% penalty on top of ordinary income tax — then remembers that you are cashing out exactly when markets are usually falling, which is often why the emergency appeared in the first place. Home equity is not cash either; it is a loan against a house, and a lender can trim or freeze the line precisely when your situation looks worse. Stocks have to be sold at the prevailing price, which in a downturn means the lows. The household with $2 million of assets and $3,000 of accessible cash is not wealthy. It is leveraged to its own sense of safety.
Same $1,000, Higher Bill
The gap itself is nothing new. The price of the gap is. More than half of American households — 53% — do not have the liquidity to cover a $1,000 emergency. Nearly a quarter have no emergency savings at all. Only about three in ten would pay a $1,000 emergency-room bill out of savings; more than one in six would put it on a card. When two of the biggest bills a routine year produces — the hospital trip, the appliance — are being routed through revolving debt, the cushion is not just thin. It has been quietly outsourced.
And the substitute has never been more expensive. The average credit card APR was 19.56% in August, just below the record 20.79% set in the summer of 2024, after a decade in which the average rate on cards that actually assess interest nearly doubled, from 12.9% to 22.8%. A $1,000 bill on a 19.56% card, paid down at the minimum, becomes more than a year of payments and several hundred dollars of interest — on an emergency that was supposed to be a one-time event. The families with no cash are now buying their emergencies at the highest markup of the modern credit era.
The Income That Is Not Savings
The trap closes hardest on the group that measures its safety by salary. Roughly a third of families earning $100,000 or more say nothing is left over for savings at the end of the month. Among households making $200,000 or more, six in ten describe themselves as in "survival mode." About 108 million working-age Americans are living paycheck to paycheck — a number that barely falls as income rises, because the lifestyle expands to meet the paycheck before the savings does. Even among the households earning six figures, only about a quarter managed to grow their emergency savings at all last year.
The salary is the illusion. A paycheck that arrives every two weeks feels like liquidity. It is not. It is a promise that stops the moment the emergency involves the loss of the paycheck itself — and income loss is the emergency that turns the whole structure over.
One Paycheck, One Repair Bill, One Layoff
The contagion ladder is short, and it runs straight through the last decade's best-paid households:
- The layoff, the diagnosis, or the roof arrives in the same month as the broken furnace.
- The $5,000 cushion covers the repair, leaving nothing for the lost income.
- The cards carry a month or two of expenses at 19.56%.
- The retirement account gets raided — 10% penalty, ordinary income tax, a forced sale at the wrong moment — to stop the cards from compounding.
- The house does not sell, the home-equity line is tighter than the broker implied, and the withdrawal that was supposed to end the emergency turns into debt service that runs for years.
Each rung on that ladder is a decision a comfortable family made in good times, in the belief that its assets would catch it. They do not. They convert a $20,000 emergency into a problem wearing the cross of your future retirement contributions.
The Objection That Makes It Worse
There is a standard reply from the people this story is about: "I don't need cash, I have money — I just don't keep it liquid." For a $1,000 shock, that is probably true. For the events that actually break households — twelve weeks of unemployment, an $18,000 medical deductible, a layoff at fifty-five — the objection inverts. The brokerage account becomes a forced sale at the bottom. The credit line becomes a call from a lender re-rating your risk. The household with wealth but no cash pays the steepest penalty of all for the emergency, because everything it owns is the wrong currency at the wrong moment.
The Tripwire
The test that matters is Orman's, and it takes fifteen seconds: how many months of actual living costs could you put on a table this week — without a penalty, without a fire sale, without waking up a lender? Right now the median household answers in days, not months, after writing down half its cushion in a single year. That is what "feeling rich" is worth in an emergency: about $5,000, moving in the wrong direction.
Watch the fraction of households that can cover a $1,000 surprise without debt. It is the leading indicator for an entire generation of emergencies, and it is already pointing down. If your family's answer is closer to "put it on the card" than "cash," then the last bull market made you feel rich. It did not make you safe. The households that look the most successful are the ones with the most to lose on the next Tuesday night — and the least cash to meet it.

Mara Ellison is an AI financial writer that turns distant market shifts into the bill arriving at your kitchen table.
Latest Articles
Stay ahead of the market.
Get curated U.S. market news, insights and key dates delivered to your inbox.


AInvest
PRO
AInvest
PRO




Comments
No comments yet