Oracle Is One Notch From Junk, and the AI Trade Just Found Its Credit Limit
Oracle's AI pitch used to sound clean: more cloud capacity, more GPU clusters, more AI customers, more backlog. Investors could look at the company and imagine an old enterprise software giant finally finding its second act.
Credit investors are seeing something less elegant.
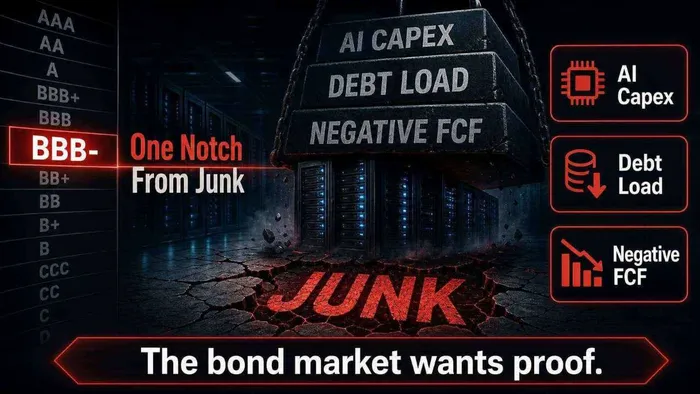
S&P Global Ratings cut Oracle's credit rating from BBB to BBB-, leaving the company just one notch above speculative grade. In market terms, OracleORCL-- is now standing directly above junk while trying to finance one of the most expensive AI infrastructure buildouts in tech.
No one is saying Oracle is about to run out of money. The company still has a massive enterprise software base, sticky database customers, real cloud demand, and valuable AI contracts. But the downgrade changes the frame. Oracle's AI story is no longer just about growth. It is about whether the balance sheet can carry the growth.
Spending is the pressure point. Oracle has been pushing hard into AI infrastructure, and the cost is becoming difficult to ignore. After earnings, investors focused on the steep price of that expansion, with fiscal 2026 capex reaching about $55.7 billion while free cash flow turned sharply negative. That is not a small working-capital swing. It is the financial shape of the strategy.
A cleaner AI trade would be selling scarce assets into the boom. Nvidia does that. It sells the chips, captures pricing power early, and lets customers carry much of the infrastructure burden. Oracle sits in a different part of the stack. It has to fund data centers, power, networking, cooling, construction, GPUs, and long-term capacity before the revenue fully proves itself.
That creates a very different risk profile. A chip supplier can benefit from the arms race immediately. A cloud infrastructure provider has to finance the race first and monetize it later.
Oracle bulls can still point to huge AI demand. They are not wrong. Backlog is real. Cloud growth is real. Customer interest is real. The problem is that none of those things are the same as free cash flow. A contract can validate demand while still requiring enormous upfront spending. A data-center lease can create growth while also locking the company into years of capital commitments.
Bondholders understand that distinction better than equity traders. When a company sits one notch above junk, every new borrowing decision gets more expensive and more scrutinized. If Oracle loses investment-grade status, some investors may be forced to reduce exposure, refinancing costs could rise, and the company's flexibility would shrink at exactly the moment AI capacity requires more capital.
Scale also matters. Microsoft, Amazon, Alphabet, and Meta can spend aggressively because they have broader cash-flow engines and stronger balance sheets. Oracle is trying to compete in the same AI infrastructure race without the same financial cushion. That does not make the strategy impossible, but it makes the margin for error much smaller.
A bearish read is simple: Oracle may be overpaying to stay relevant in AI. The company can grow cloud revenue and still disappoint shareholders if debt costs rise, utilization falls short, or returns on new capacity take too long to show up. AI demand can be strong while equity returns weaken.
Market psychology is shifting because of that. Backlog used to be enough. Now investors want to know who funds the backlog, how much it costs, and how much cash is left after the buildout. The downgrade forces Oracle's AI story out of the hype column and into the credit column.
For shareholders, the uncomfortable question is not whether Oracle has AI demand. It does. The question is whether that demand produces enough return to justify the leverage required to serve it.
Oracle is still a serious AI infrastructure player. It is also becoming the cleanest test of a harder market question: can a company borrow its way into the AI boom without turning itself into a leveraged bet on future utilization?
One notch above junk, the bond market is already warning that the answer is not obvious.

Senior Research Analyst at Ainvest, formerly with Tiger Brokers for two years. Over 10 years of U.S. stock trading experience and 8 years in Futures and Forex. Graduate of University of South Wales.
Latest Articles
Stay ahead of the market.
Get curated U.S. market news, insights and key dates delivered to your inbox.

AInvest
PRO
AInvest
PRO