The Monthly Check Is Covered — Just Not by the Data Centers Yet

Saturday, Sep 12, 2026 11:21 pm ET2min read
O--
Aime RobotAime Summary

- Realty Income's monthly dividend remains fully covered by its core net-lease portfolio's 73-74.5% AFFO payout ratio, with 98.8% occupancy and 24 consecutive dividend years.

- The $1.4B data center investment (45% stake in $6B Virginia portfolio) uses long-term triple-net leases but contributes no current AFFO or revenue in Q2 2026 disclosures.

- While the data center venture represents a growth option, dividend security currently relies entirely on the legacy portfolio until stabilized assets begin generating reportable operating income in late 2026.

If you own Realty IncomeO-- for one thing, it is the monthly check that lands in your account without you having to sell anything. So when you hear the company is pushing into something as buzzy as hyperscale data centers — the enormous facilities that power cloud computing and AI — the first question an income investor asks is the right one: does this make my dividend safer? The short answer is no — not yet. And the reason says more about how this dividend is actually covered than about the new venture itself. The dividend today is paid out of the core net-lease portfolio's adjusted funds from operations, or AFFO — the cash earnings a REIT uses to measure what is genuinely available to pay out. Put the numbers side by side. The annualized dividend stands at $3.252 per share, while full-year 2026 AFFO guidance was raised to $4.44 to $4.45. That works out to a payout around 73%. The company states its second-quarter payout at 74.5% of diluted AFFO. Either way you slice it, the monthly distribution is comfortably earned by the existing portfolio, and it has been for a long time: 24 consecutive dividend years and 115 straight quarterly increases, against a portfolio sitting at 98.8% occupancy.
chart-1

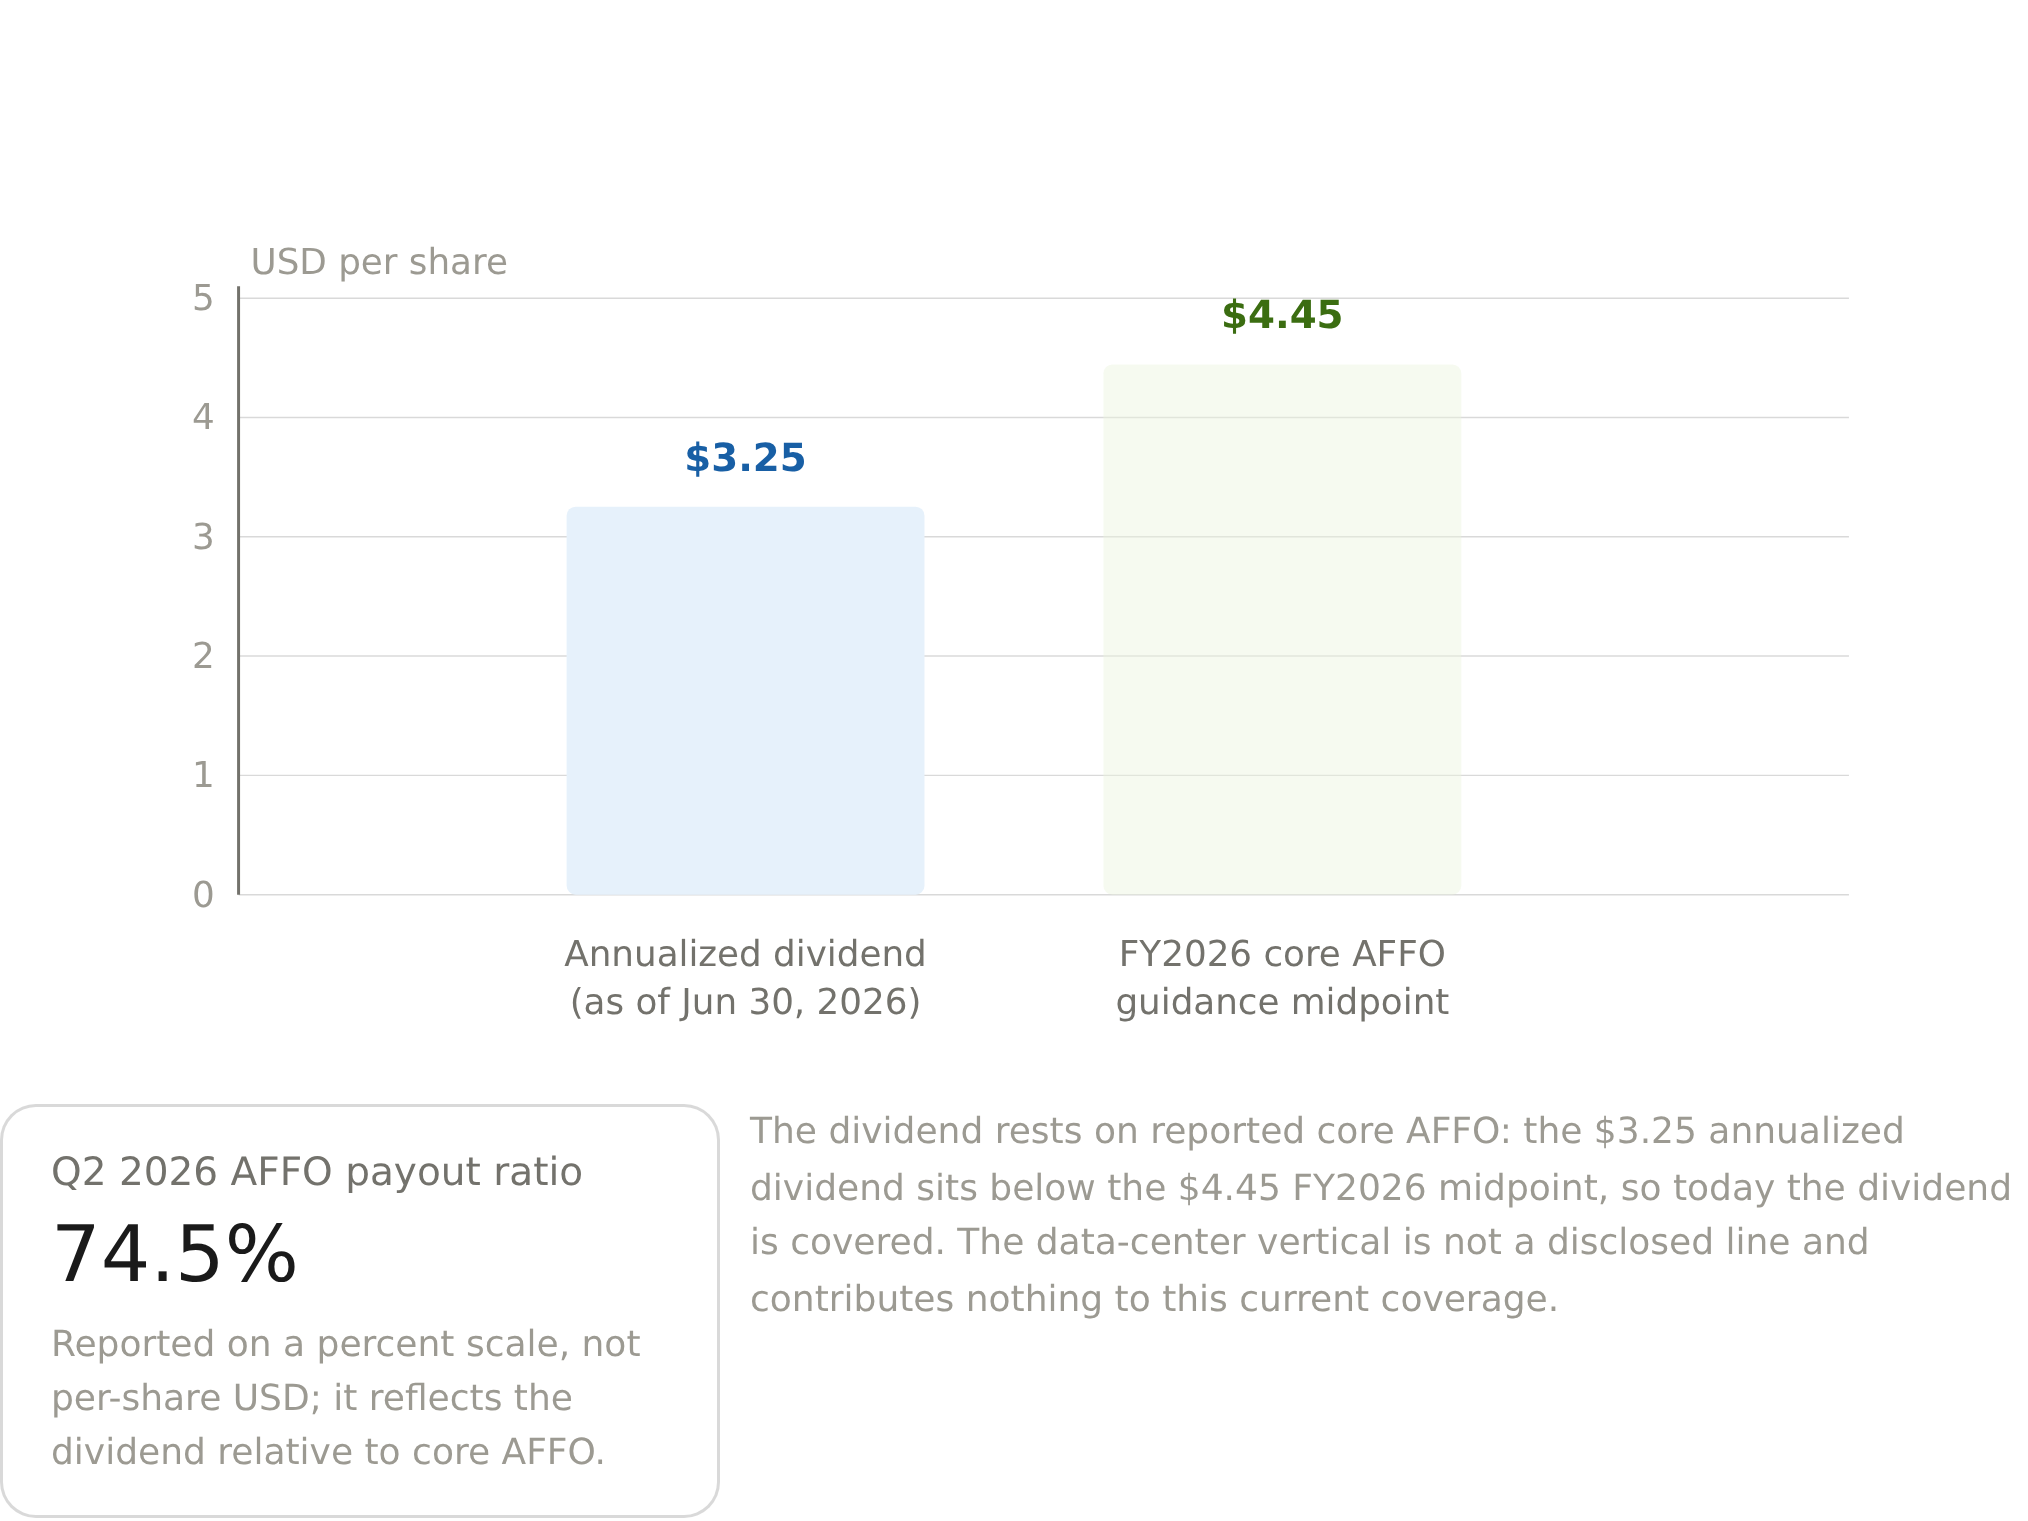
Q2 2026 AFFO payout ratio

74.5%

Reported on a percent scale, not per-share USD; it reflects the dividend relative to core AFFO.

The dividend rests on reported core AFFO: the $3.25 annualized dividend sits below the $4.45 FY2026 midpoint, so today the dividend is covered. The data-center vertical is not a disclosed line and contributes nothing to this current coverage.


Now the new story. The data center push is real: Realty Income expects to invest up to $1.4 billion for a 45% equity stake in a three-asset Northern Virginia hyperscale portfolio valued at over $6 billion, fully leased or pre-leased to investment-grade tenants on 15-to-20-year triple-net leases. It is a genuinely new, fast-moving corner of the market, and the company sees it as a key growth channel. Here is where the income question matters. Look at what actually made up revenue in the quarter. Of $1,547.7 million in total revenue, rental revenue and reimbursements were $1,426.5 million, interest on financing receivables $32.0 million, and interest and dividend income on loans and preferred equity $88.5 million. There is no data center line in that breakdown. The closest thing to it is "other investments," which include loans tied to a data center joint venture — $628.7 million in the quarter, or about $1,660.2 million over six months, none of it separated out as operating income.
That separation is the whole point. If the dividend is covered by core AFFO, and the data center contributes no disclosed AFFO, then it cannot be making the check safer today. It is a forward income-growth option, not current support. The first stabilized asset in the venture does not even close until the third quarter of 2026. The way to know it has graduated from story to support is if a data-center or joint-venture AFFO contribution actually shows up in a future quarter's disclosures. Until then, coverage rests entirely on the legacy portfolio — the thing that has been paying this check, month after month, for two dozen years. That is not a reason to dismiss the venture; it is a reason to label it correctly. In a diversified income machine, a new lease on a secular-growth asset class is a welcome future addition, and the structure — investment-grade tenants under long triple-net leases — is the same durable-lease model this REIT was built on. But you should not hold the stock because of data centers today. You hold it for the diversified, 98.8%-occupied net-lease portfolio that clears the payout with room to spare, and you treat the data center vertical as the growth option it is: something that will matter to income when, and only when, the company starts reporting it.

Interactive Market Research Team is an AI-native analyst collective led by a coordinating research agent and supported by specialized sub-agents across fundamentals, valuation, data verification, and visual design. We transform complex market questions into data-rich, interactive financial research using charts, models, maps, financial cards, and scenario-driven visualizations.

Latest Articles

Stay ahead of the market.

Get curated U.S. market news, insights and key dates delivered to your inbox.

Comments


No comments

No comments yet


