

Micron's fiscal third quarter was a record, but the record is not the story. For the quarter ended in June, the company reported $41.5 billion in total revenue, up 74% from the prior quarter and 346% year over year, with adjusted earnings of $25.11 a share against roughly $19.82 the Street expected. Gross margin hit 84.9%, up ten percentage points sequentially. It was the kind of beat that re-rates a stock, and shares rose about 4% after hours when management followed it with guidance of roughly $50 billion for the next quarter.
The number an investor should actually be holding onto sits inside that total. Data-center revenue alone exceeded $25 billion in the single quarter — while the entire company, all products, had produced only about $9.3 billion in revenue a year earlier. One sub-segment has now outgrown what used to be the whole company.
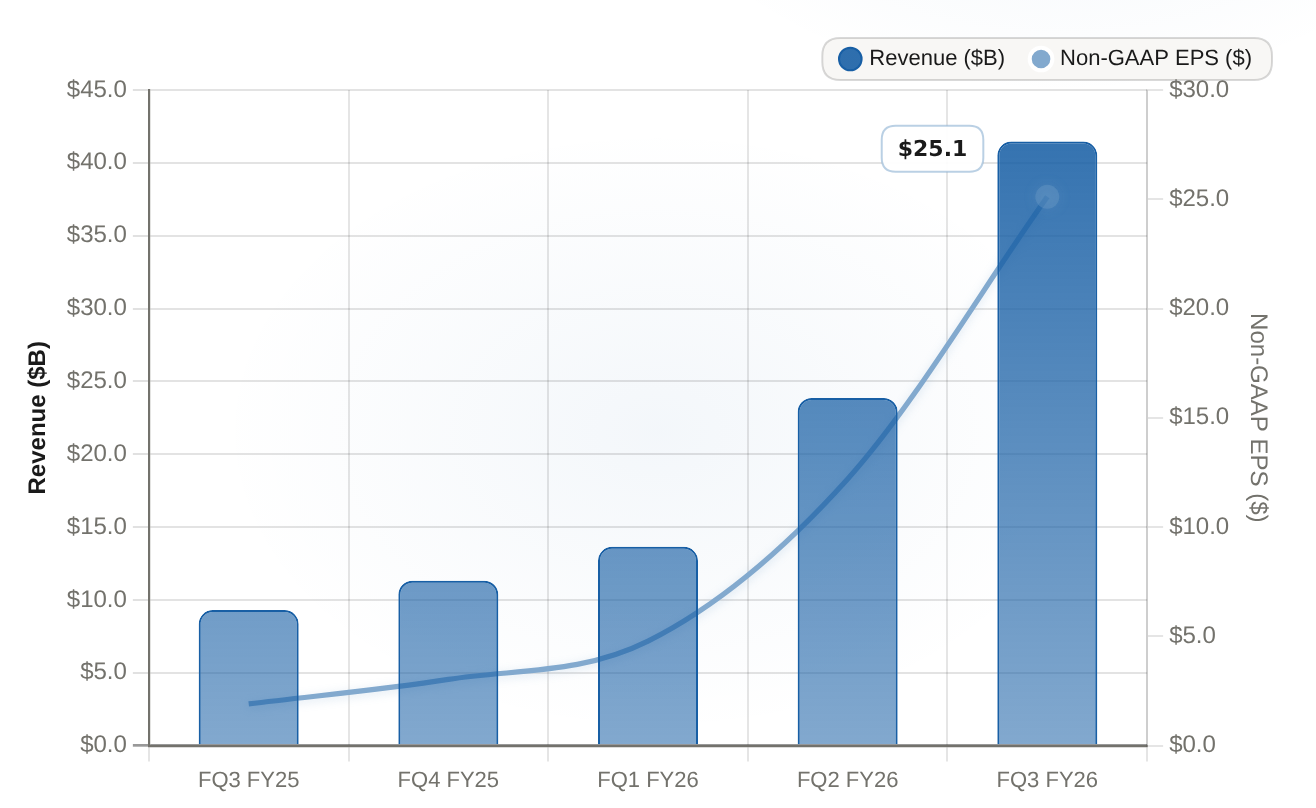
Revenue and non-GAAP EPS inflected sharply in fiscal Q3 2026 (revenue $41.5B, EPS $25.11), with Micron notingMU-- data-center revenue above $25B in a single quarter and DRAM at ~76% of revenue. Management guides Q4 FY26 to roughly $50B revenue (forward-looking guidance, not reported), which extends the ramp beyond the plotted quarters.
| Period | Revenue ($B) | Non-GAAP EPS ($) |
|---|---|---|
| FQ3 FY25 | 9.301 | 1.91 |
| FQ4 FY25 | 11.315 | 3.03 |
| FQ1 FY26 | 13.643 | 4.78 |
| FQ2 FY26 | 23.86 | 12.2 |
| FQ3 FY26 | 41.46 | 25.11 |
The ramp is visible as a curve that stops being gradual. For four quarters revenue climbed steadily; then the latest quarter jumped 74% sequentially to $41.5 billion, with adjusted earnings following the same slope up to $25.11 a share. That steepening at the end is where the read changes from a memory recovery into a sub-segment inflection.
What is driving that cliff is not the memory market broadly. DRAM, the workhorse chip that feeds the AI accelerator, brought in $31.3 billion, about 76% of total revenue and up 343% year over year. And the premium engine within DRAM is high-bandwidth memory, or HBM — the stack of memory cells seated next to the AI chip to shovel data in and out fast. Micron's HBM4 has been certified by Nvidia for the Vera Rubin AI platform, is volume-shipping at premium pricing on capacity the company says is sold out through 2026.
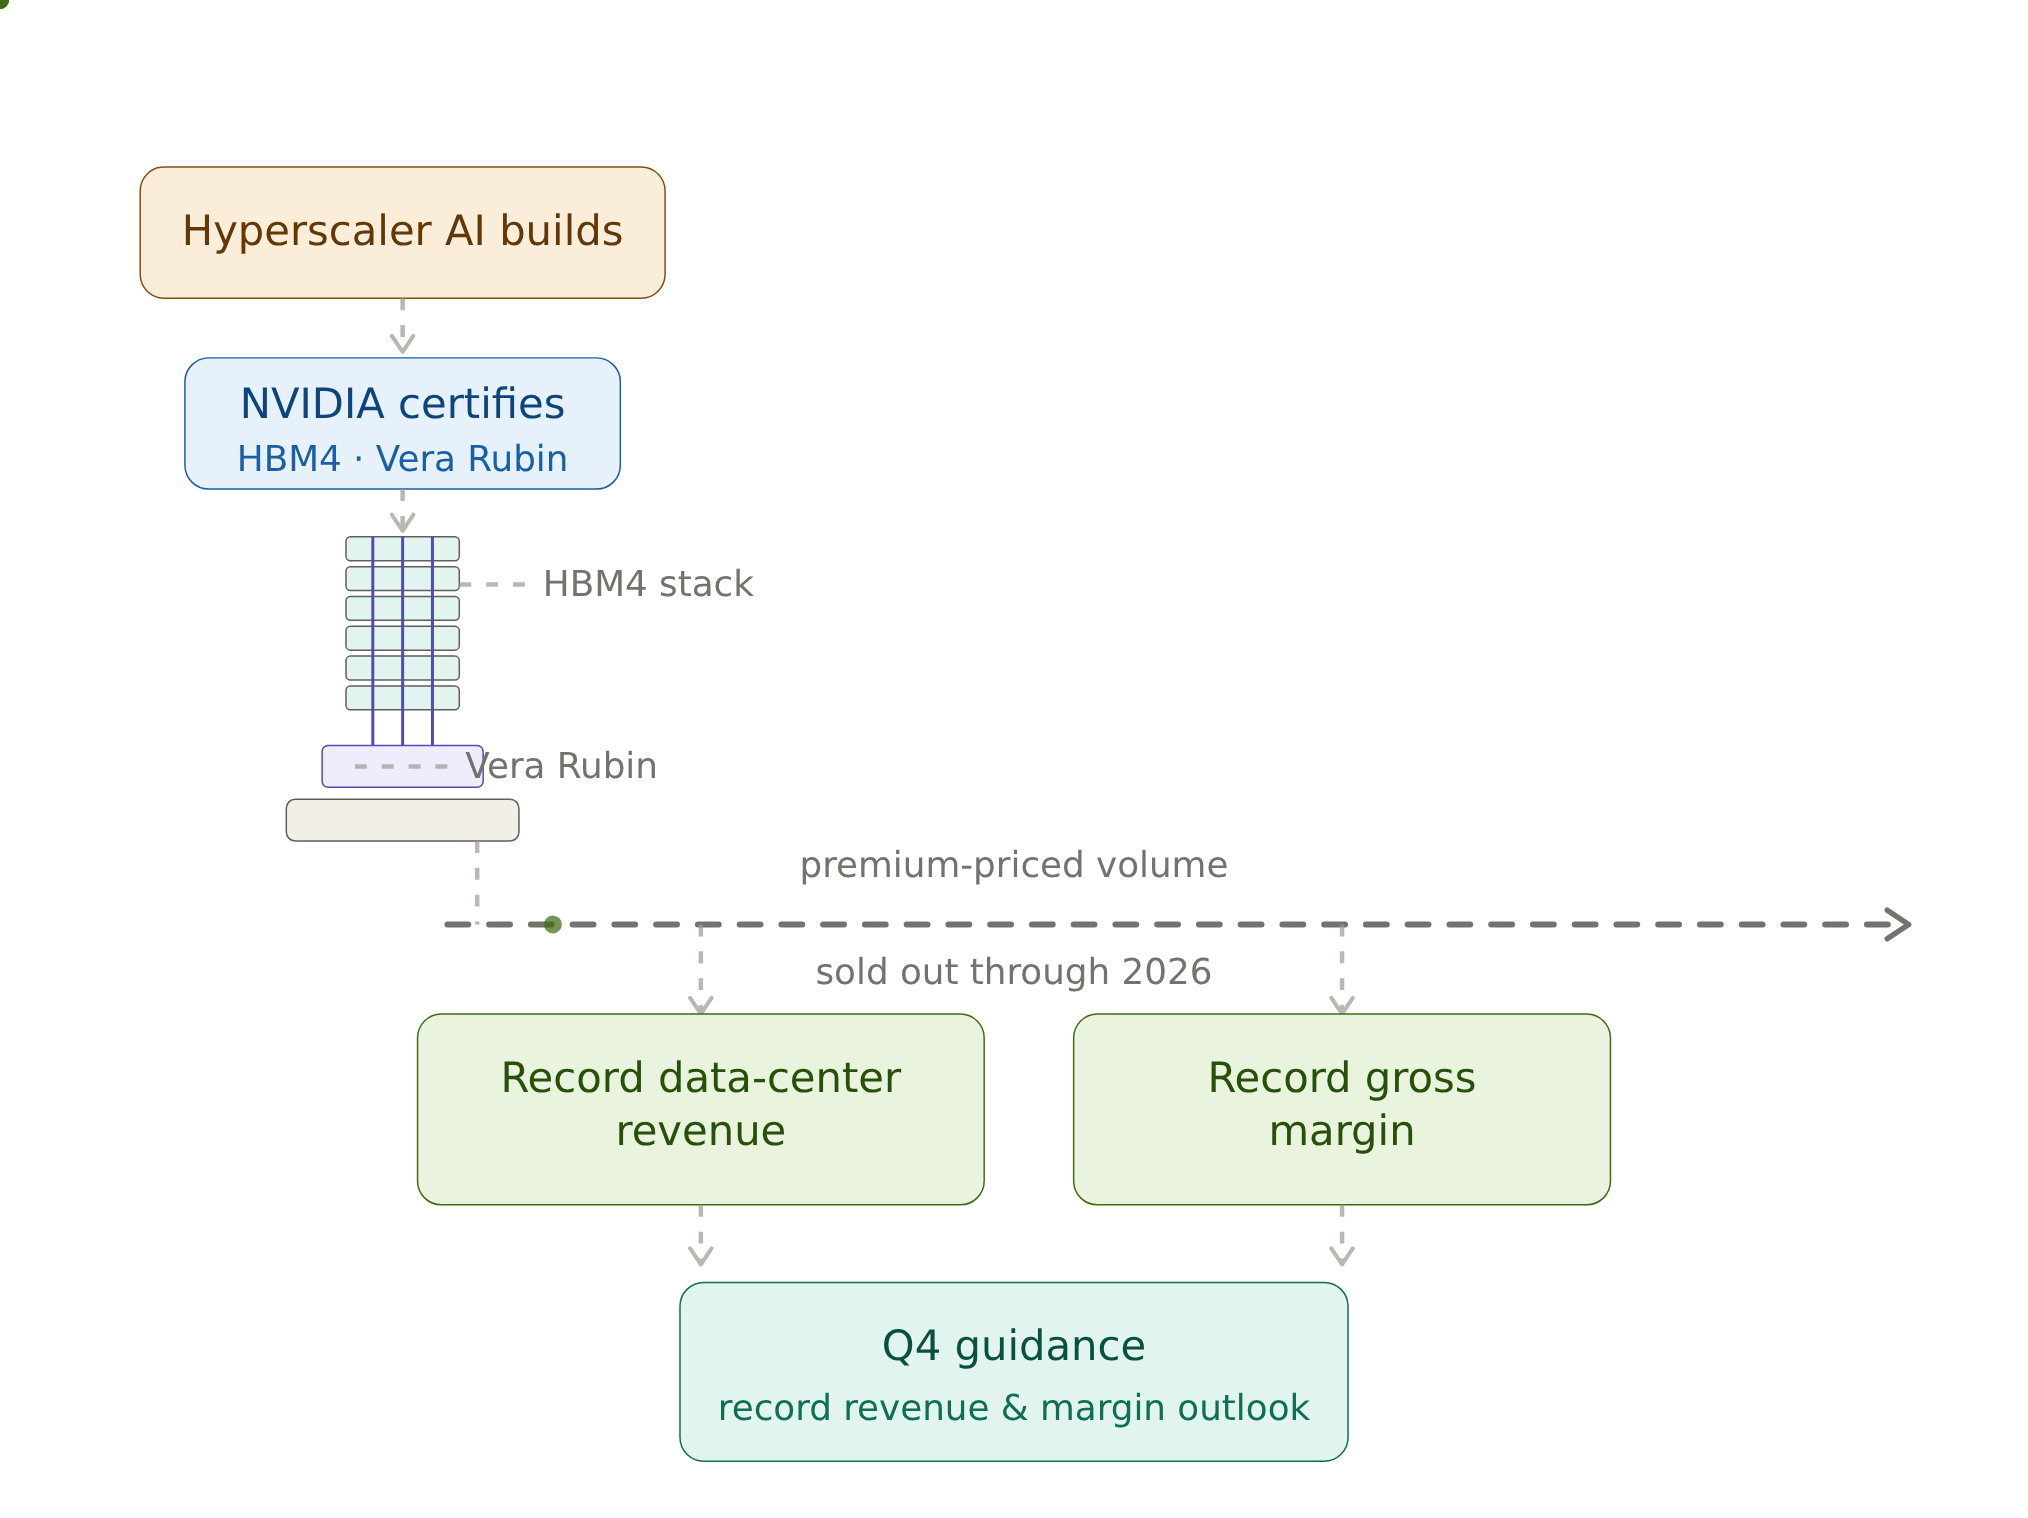
That is the mechanism, and it matters because it changes what kind of business this is. In the prior cycle, memory was a commodity that rose and fell on how much of it anyone could manufacture. HBM turns it into an AI-infrastructure asset — a scarce, premium-priced input with a named customer and sold-out supply. The difference is the difference between a company growing quickly and a company compounding off a structural bottleneck its competitors also want.
The forward guide is where the durable-versus-transient question gets sharp enough to test. Management guided the fiscal fourth quarter to roughly $50 billion in revenue, about 86% gross margin, and about $31 of adjusted earnings, plus or minus a dollar. On a run-rate basis that is a $200 billion annualized revenue clip.

Here is the honest tension the quarter leaves unresolved. The durable-inflection thesis is forward-looking and untested at this writing — it rests on an HBM/data-center ramp repeating, not on the one record quarter being real. And the Street has already raced ahead of even the company's own number: Ainvest data shows consensus for the Q4 report had climbed to roughly $73 billion in revenue, well above Micron's official ~$50 billion guide. A large share of the re-rating is now priced against estimates that are already aggressive.
So the separation an investor makes is not bullish or bearish. It is whether MicronMU-- is growing into its multiple or whether the market is paying up for a single record quarter. The next report, due around September 30, is the test: does fiscal Q4 revenue land near the ~$50 billion official guide, and does data-center demand hold? If it does, the sub-segment inflection has legs. If it lands well short, the premium was pricing a ramp that did not sustain.








Comments
No comments yet