

Tuesday's most decisive moves are best read as an earnings-quality test, and the tape graded them before most of us finished the press releases. FabrinetFN-- (FN) rose about 5% to roughly $598.58 because the record in its AI-optical quarter survived inspection: revenue beat both guidance and consensus, the guide for next quarter stayed strong, and the stock earned the move. FlexsteelFLXS-- (FLXS) fell about 4% to roughly $70.86 while touting "record" GAAP earnings per share — an apparent contradiction that resolves the instant you see the $9 million one-time refund and the buybacks hiding behind the headline number. When a stock sells off on a record quarter, the market is usually reading the fine print. This time it read it correctly.
Fabrinet: the record that held up
Fabrinet is the contract manufacturer that builds a significant share of the industry's 800G optical transceivers — the modules shuttling data inside hyperscaler AI clusters — so its fourth quarter was always going to be a sector event, and the print delivered. Revenue of $1.316 billion was up 45% year over year, a record, while non-GAAP (adjusted) EPS of $4.10 beat the ~$3.81 consensus by 7.5% and the midpoint of the range the company had guided for: $1.25-1.29 billion in revenue and $3.72-3.87 in non-GAAP EPS. It was the fifth straight quarter Fabrinet has beaten expectations, and the guide extends the run — Q1 FY27 revenue of $1.375-1.425 billion with EPS of $4.10-4.25, a midpoint roughly matching what the just-reported quarter delivered, which management described as "durable" demand heading into fiscal 2027.
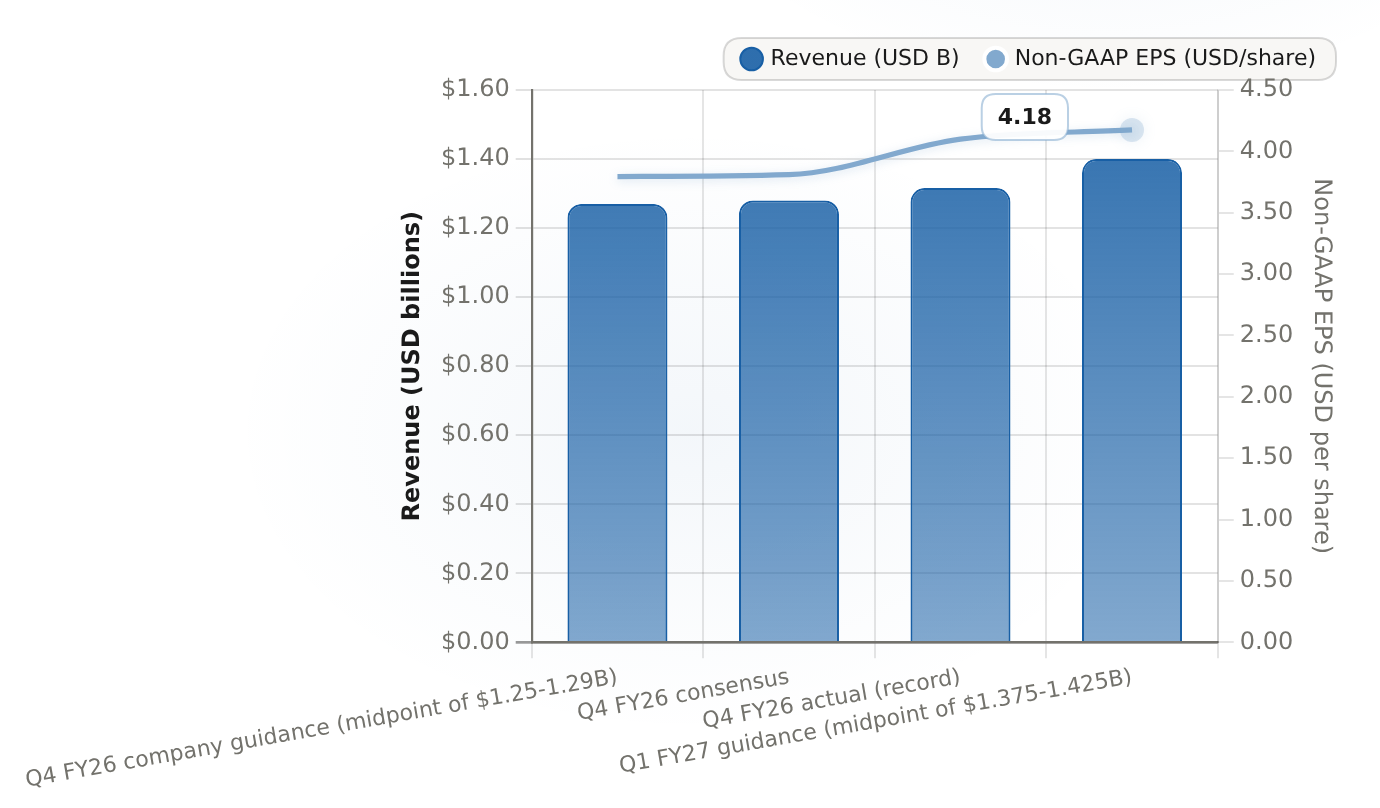
Fabrinet's Q4 FY26 actual cleared both company guidance and consensus on revenue AND EPS, and the Q1 FY27 midpoint guide lands above the just-reported record — a durable ramp that supports following the stock.
| Scenario | Revenue (USD B) (B) | Non-GAAP EPS (USD/share) |
|---|---|---|
| Q4 FY26 company guidance (midpoint of $1.25-1.29B) | 1.27 | 3.795 |
| Q4 FY26 consensus | 1.28 | 3.81 |
| Q4 FY26 actual (record) | 1.316 | 4.1 |
| Q1 FY27 guidance (midpoint of $1.375-1.425B) | 1.4 | 4.175 |
A beat plus a non-decelerating guide is the recipe that makes a bellwether print followable rather than frothy. The question is what it costs to own the follow-through, and here Fabrinet is spending aggressively: capacity, rather than orders, is now the binding constraint, and the company is building toward the ramp — inventories reached about $1.02 billion, net property, plant and equipment nearly doubled year over year, capital expenditures surpassed operating cash flow, and quarterly free cash flow was negative at -$36.9 million. For a company that grew full-year revenue about 36% to roughly $4.6 billion, that is the price of locking in 800G share before hyperscalers take the capacity elsewhere; it is reinvestment, not over-earning.
The valuation layer is where the picture gets honestly murky. The trailing multiple is stable at about 51x earnings across sources, but the forward P/E has not settled: the live market tape shows roughly 64x, while MarketBeat's refreshed estimate set puts it nearer 46x. Treating forward valuation as a single number right now would be fake precision — consensus is still being rebuilt after the report — so the honest framing is a wide band with the fundamental question (how much 800G upside to believe in) doing all the work. Per Ainvest's technical snapshot, price sits above both the 50- and 200-day averages with RSI near 63: momentum is positive, which is exactly why this reads as a "wait for a better entry," not a "chase the up-day."

The read-through: Coherent and Ciena are priced for perfection
Fabrinet is the industry's primary contract manufacturer of 800G optics, so analysts read its order commentary and 800G ramp language as the bellwether that resets demand expectations across the optical complex — Lumentum, Coherent, Applied Optoelectronics, Ciena. Tuesday's beat was taken as confirmation, and the group moved.
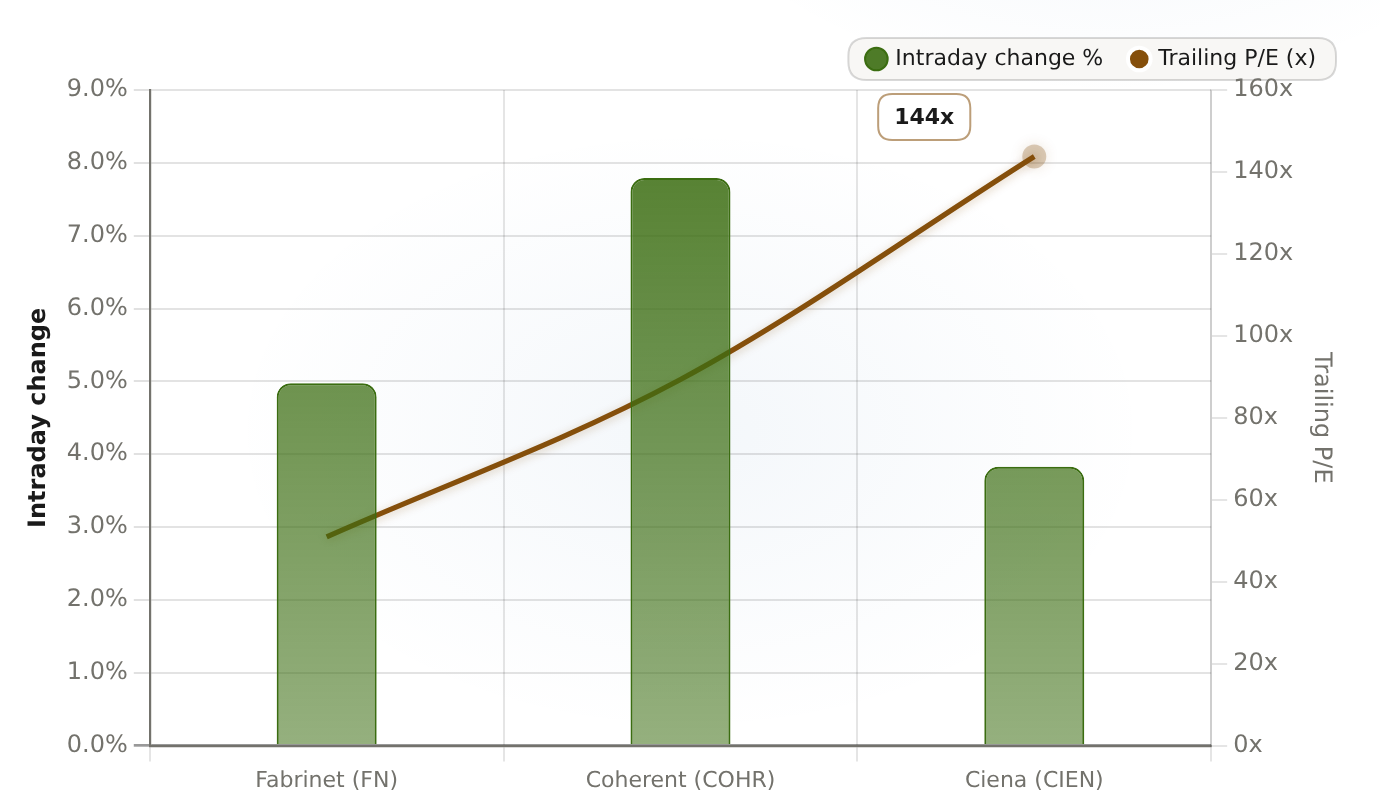
Coherent led Tuesday's read-through at +7.8% ahead of Fabrinet (+5.0%) and Ciena (+3.8%), yet the group's trailing P/E of 51x-144x shows little valuation cushion on the AI-optical move.
| Ticker | Intraday change % | Trailing P/E (x) |
|---|---|---|
| Fabrinet (FN) | 4.974 | 50.95 |
| Coherent (COHR) | 7.792 | 89.34 |
| Ciena (CIEN) | 3.827 | 143.78 |
By Ainvest's close snapshot, Coherent rose 7.79% to $351.22 and Ciena rose 3.83% to $445.18 — the optical names that were the market's momentum darlings from earlier this year extending their run on the read-through. The problem is what the confirmation now costs: at roughly 89x and 144x trailing earnings respectively, against Fabrinet's ~51x, this is a group that has been repriced for a flawless 800G ramp. There is little cushion in a ~51x-to-144x trailing band, so the same read-through that lifted COHR and CIEN today could de-rate them hard on a soft AI-optical print from any one name. Momentum is confirmation, not valuation; at these multiples, one decelerating quarter inverts the trade.
Flexsteel: a "record" built on a refund
Flexsteel's quarter is the cleanest earnings-quality lesson on today's tape. The furniture maker reported net sales up just 0.7% year over year to $115.4 million versus $114.6 million a year earlier, yet GAAP diluted EPS printed a record $2.58, up 36.5% — and the stock still fell about 4% to ~$70.86, closing right at its 50-day moving average of ~$70.87 with RSI near 40, per Ainvest data. The market is not confused; the record is manufactured.
The plumbing: the record rides on a one-time $9.0 million IEEPA tariff refund (IEEPA, the International Emergency Economic Powers Act, being the authority under which the duties were imposed) that flowed through cost of goods sold and added roughly 780 basis points to GAAP gross margin, lifting it to 30.0% from 23.9% a year earlier. On top of that, $63.7 million of FY26 buybacks shrank the share count to 4.9 million from 5.7 million. A refund through the cost line plus a smaller denominator: that is how you get "record" per-share earnings out of a quarter with flat revenue.
Strip the one-time items out and the underlying operation deteriorated. Adjusted EPS fell 5% year over year to $1.33, below the roughly $1.52 consensus per Ainvest's estimate data, on an adjusted operating margin that compressed to 7.1% from 9.0% — dragged down by a peso-denominated currency headwind on Mexican assets and the exit of the ready-to-assemble "homestyles" category. And the guide confirms the spike does not persist: Q1 FY27 net sales of only $111-115 million (1-4% growth) with GAAP operating margin guided to 6.5-7.0%, a bright-line step down from the refund-boosted 14.2% Q4 print. Flexsteel also raised its dividend 25% in June 2026, which is fine capital stewardship — but it is not earnings power.
The watch signals are straightforward. I want to see whether adjusted operating margin at least stabilizes before the refund anniversary in Q4 FY27 — the quarters without the refund are the honest test. Note the ~18.8x forward P/E on the valuation tape: it only looks cheap because it is computed against a depressed, normalizing adjusted-EPS base. If adjusted profitability keeps sliding, that multiple is a value trap in disguise, and treating today's $2.58 GAAP print as run-rate earnings would be the false signal to avoid.
The action: follow Fabrinet, fade Flexsteel, respect the multiple
On a multi-quarter horizon, the split is clean. Fabrinet is the mover worth acting on — with conditions rather than urgency. The record beat, the "durable" guide, and the capacity build earn the position; the unsettled forward multiple does not earn a chase, so the lower-risk entry is on weakness or on confirmation that the 800G ramp is converting capacity into revenue. The thesis-failure condition is a future print in which AI-optical order visibility or 800G ramp rates soften — which would invert the whole complex, and that is exactly why Coherent at ~89x and Ciena at ~144x trailing warrant caution despite today's confirmation.
Flexsteel is a fade/wait, not a buy and not a short. Nothing in the print says the company is broken — this is ordinary cyclical and currency damage, not a moat that cracked. But a manufactured record is not yet a contrarian setup: the market's ~4% discount is the correct read until the underlying operation, rather than a refund, shows it can hold margins. That test lands in the next two quarters. Don't let a headline record that was purchased with a one-time refund talk you into a position the fundamentals haven't earned yet.








Comments
No comments yet