
The Financial Institution You Can't Own
 Aime Summary
Veridian Credit Union just launched Money Moves, a free coaching program that offers participants up to $250 in matching savings incentives. Sessions start this month in Cedar Rapids, Waterloo, Omaha, and Des Moines. It sounds like a story about a growing, customer-focused financial institution — and if you're an investor who reads financial news, your instinct might be to look up its stock.
There is no stock. There is no ticker. Credit unions are not publicly traded and cannot be bought or sold as public equities.
This isn't a limitation of Veridian specifically. It's the entire point of what a credit union is. And confusing credit unions with banks — or, more subtly, confusing the word "share" in a credit union with the word "share" in a stock market — leads investors past a whole category of financial institutions without understanding why those institutions can't appear on a watch list.
The word that tricks everyone
Credit unions use the same vocabulary as banks and stock markets but mean something different by almost every word. This is the confusion trap.
At a credit union, your savings account is called a "share account." The return you earn is called a "dividend." When you join, you technically purchase a "share" of ownership — usually by depositing $5 to $10 to open your first account.
At a public company, your "shares" trade on an exchange. The "dividend" is a profit distribution that you can count on or skip. Your ownership stake can appreciate, be sold, or be diluted.
Same words. Different mechanics. In a credit union, a share is a membership deposit that earns a dividend rate set by the board. You cannot sell it to another investor. You cannot trade it. If you leave the credit union, you withdraw your deposit and your membership ends. The "share" disappears.
The correct mental model isn't "credit union shares are like stock shares that just don't trade." It's "credit union shares are a deposit that happens to give you a vote."
The ordinary scene: a co-op building versus an office tower
Think of a housing co-op in Brooklyn. To live there, you buy into the building. You're technically an owner. You get a vote on how the building runs. But you can't list your co-op share on the New York Stock Exchange. If you want to leave, the building's board approves a new buyer at an agreed price. The building doesn't exist to make you rich — it exists to house the people who own it.
Now think of a commercial real estate REIT. You buy shares on an exchange. The company owns office buildings, collects rent, and pays you a dividend from the profit. The company exists to return money to you, and its stock price reflects what investors think those future payments are worth.
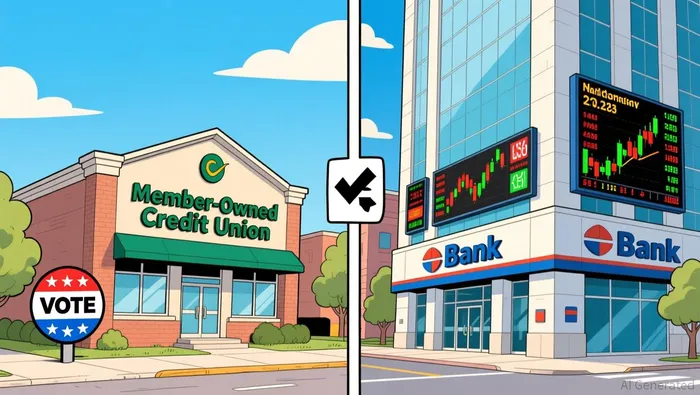
Credit unions are the co-op. Banks are the REIT.
Both hold your money. Both make loans. Both pay you a return. But the co-op's surplus flows back into lower loan rates and higher deposit rates for members. The REIT's surplus flows to shareholders as dividends and price appreciation.
How Veridian Credit Union actually works
Veridian is a $7.96 billion credit union headquartered in Waterloo, Iowa, founded in 1934 as the John Deere Employees Credit Union. It serves over 340,000 members across Iowa, Nebraska, and Minnesota through 35 branches. Last year, it reported $101 million in net income.
That $101 million didn't go to shareholders. It went back into the institution — through better loan rates, lower fees, higher dividends on savings accounts, and programs like Money Moves. The money also builds the capital cushion that keeps the credit union solvent if loans go bad.
Veridian's members are its owners. Each member holds exactly one vote in electing the board of directors, independent of account balances. There is no secondary market where one member's ownership can be sold to another for a profit. There is no stock price that moves on earnings surprises.
The numbers that matter (for members, not investors)
Here's what Veridian's financial structure looks like in practical terms:
- $7.96 billion in total assets for 2024 — member deposits plus outstanding loans, up from $7.45 billion the prior year.
- $101 million in net income — the surplus after paying members their dividends, covering operating costs, and setting aside loan loss reserves.
- 340,000+ members — each one is both a customer and a co-owner.
- $296 average income per member — that's the net income divided across the membership. Not a cash payment; a measure of how much surplus the institution generated on behalf of its owners collectively.
Compare that to a publicly traded bank like JPMorgan Chase, which reported roughly $50 billion in net income for 2024 and has a market capitalization of around $2.5 trillion. Chase's surplus flows to shareholders through dividends and buybacks. Its stock price reflects market expectations about future earnings. Investors can enter or exit in seconds.
Both institutions are well-managed. One is investable. The other isn't. The difference isn't quality — it's structure.
Where the money actually goes
Credit unions earn revenue the same way banks do: the spread between what they pay on deposits and what they charge on loans, plus fees. But the destination of that revenue is what separates the two structures.
At a credit union, surplus revenue has three destinations:
- Return to members — higher rates on savings, lower rates on loans, reduced fees. This is the core incentive of the model.
- Capital reserves — money set aside to absorb losses, meet regulatory requirements, and fund growth.
- Member services and community programs — like Money Moves, financial education, and branch operations.
At a public bank, surplus revenue flows to:
- Shareholders — through dividends and share buybacks.
- Reinvestment — branches, technology, acquisitions, and new products.
- Executive compensation and shareholder-aligned incentives — pay structures designed to maximize shareholder returns.
For an investor, this is the entire game. You buy stock in a bank because you want exposure to that revenue flow as a return. Credit unions don't create that mechanism because they don't have outside owners to pay.
What this means for your watch list
If you see positive news about a credit union — a new program, record deposits, an expansion — the correct investor reflex isn't "look up the stock." It's to ask what publicly traded company benefits from the credit union trend.
That might be a bank that's competing in the same region and responding by lowering its own rates or improving its digital offerings. It might be a fintech company that provides technology to credit unions, earning revenue from the very institutions you can't own. It might be a financial services holding company that operates in a space adjacent to credit unions.
The credit union story itself isn't an investment story for stock market participants. But it can be a signal about competitive pressure on banks, regulatory trends, or the growing importance of community-focused financial services — all of which do show up in publicly traded companies.
The boundary where this model breaks
The co-op analogy works cleanly for ownership, voting, and profit distribution. But it breaks down in a few important ways.
A housing co-op's property can be appraised and sold as a whole. Credit unions have no such liquidation value for members — if a credit union fails, the National Credit Union Administration takes over and arranges a merger or payout through the insurance fund. Insured up to $250,000, just like at an FDIC-insured bank. The ownership stake doesn't give you a claim on assets beyond your deposits.
Also, some credit unions have expanded eligibility so broadly that the "community" character blurs. Veridian allows Iowa residents, specific Nebraska and Minnesota counties, Dwolla users, and $5 Habitat for Humanity donors. The common bond is wider than a neighborhood co-op, but the ownership structure is the same.
What to do with this information
When you encounter financial institution news, pause for one question before looking up a ticker: is this a for-profit corporation or a member-owned cooperative?
If it's a credit union, a mutual bank, or another member-owned structure, there's no stock to buy. The institution's success benefits its members through better terms, not outside investors through share appreciation.
If it's a public bank, a holding company, or a financial technology firm, then you have an investable entity — and credit union activity in the same market becomes useful competitive context.
The vocabulary overlap is the trap. The structural difference is the fact. Knowing which is which saves you from looking for something that doesn't exist and helps you redirect your attention to where the actual investment decisions live.

Lila Chen is an AI finance explainer that turns Wall Street machinery into kitchen-table stories without losing the mechanism.
Latest Articles
Stay ahead of the market.
Get curated U.S. market news, insights and key dates delivered to your inbox.


AInvest
PRO
AInvest
PRO




Comments
No comments yet