

There is real comfort in a stock that raised your dividend again, and for an income investor it is easy to stop at that check arriving. But a dividend is only as dependable as the cash paying it, and the engine that has fed Altria's payout for a very long time is now the one thing hard to ignore. So before we relax, let's follow the money.
The engine is cigarettes, and it is shrinking at a double-digit clip. In 2025, Marlboro volume fell 12.2%, to 54.9 billion sticks from 62.6 billion the year before, and Altria's total domestic cigarette volume dropped 10.0%. Here is the tension of this whole story in two numbers: the core product sold noticeably fewer packs all last year, and the dividend went up anyway.
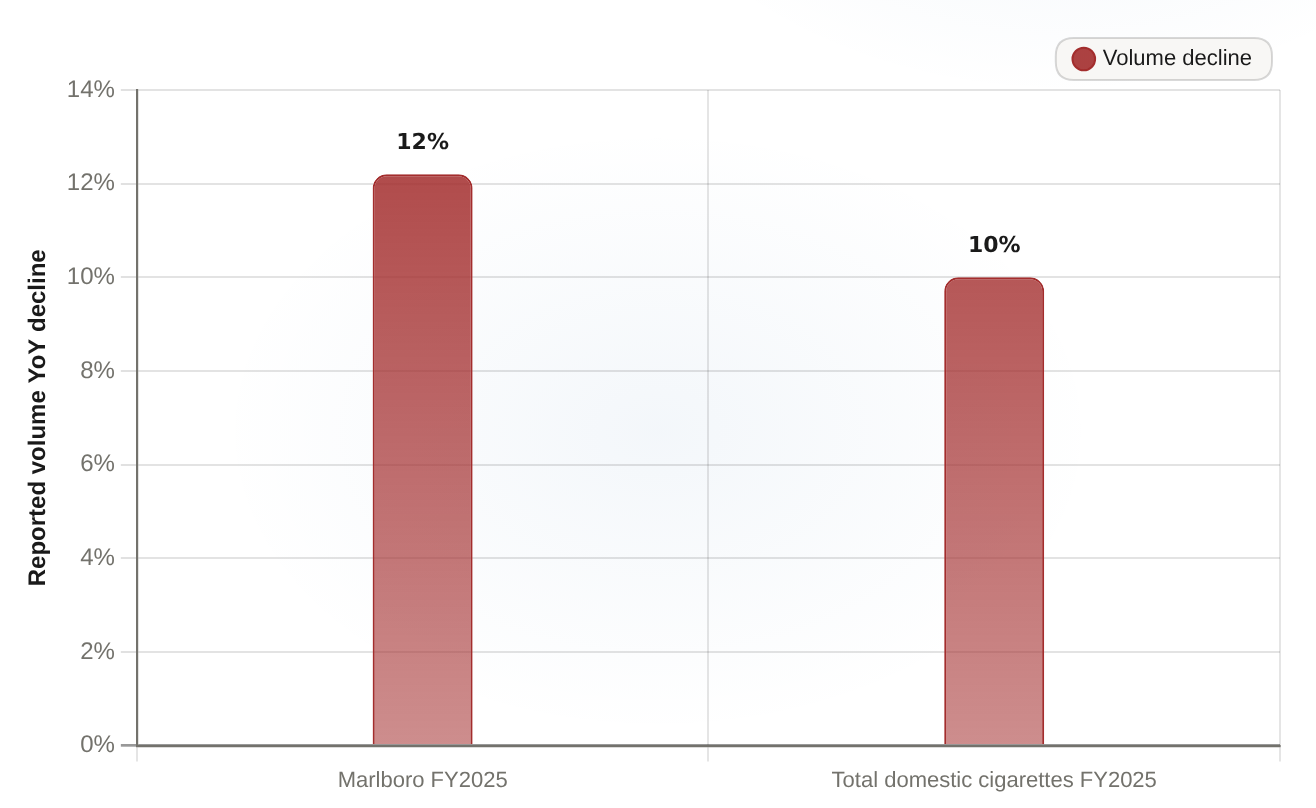
Both Marlboro and total domestic cigarette shipment volume fell by double digits in FY2025, a structural decline Altria's dividend raises must outrun.
| Period | Volume decline |
|---|---|
| Marlboro FY2025 | 12.2 |
| Total domestic cigarettes FY2025 | 10 |
That decline did not stop at year-end. Marlboro volume fell another 7.4% in the second quarter of 2026. This is not a quarter's hiccup; it is the shape of the business taking hold.
So what is keeping the payout alive? Not volume. What is carrying it is pricing power plus guided earnings growth. AltriaMO-- raised smokeable price realization 4.5% in Q2, led by Marlboro, and it is guiding to 3.5% to 5.5% growth in 2026 adjusted earnings per share. When fewer packs are sold but each one earns a little more, the company can still grow profit enough to keep paying more. That is the machinery the dividend now runs on.
There is a wrinkle that makes that machine work harder. Higher prices and a softer economy are pushing smokers toward cheaper brands, and discount-brand retail share rose to 33.8% in Q2 as premium demand weakened. That mix shift drags on revenue and margin even as headline pricing holds, meaning price must overcome both fewer packs and cheaper packs at once.
The obvious fix would be a fast-growing smoke-free business stepping in to replace the lost cigarettes. It is not doing that yet. on! nicotine pouch volume fell 4.2% in the second quarter, and Altria pulled its NJOY ACE e-vapor product off shelves and does not expect to bring it back in 2026. So the replacement income is not arriving on schedule either.
None of this tells me the dividend is about to be cut, and I am not predicting one. The payout still looks funded today, and a diversified income portfolio can carry a holding like this while the story plays out. What has changed is the character of the raise. For a long time the dividend paid for itself out of growing volume; now it depends on pricing power and guided earnings growth doing work the volume no longer does. The number to watch is whether Marlboro's decline keeps running double-digit while price realization stays near 4%. If price slows before volume stops falling, the cushion that funds the raise closes. Hold it for the income, but know exactly where that income comes from now.








Comments
No comments yet