
AECOM Rallied on a Nepal Rebuild Story. That's Not Why the Stock Moved.
 Aime Summary
The first domino is public; the next one is still mispriced.
On August 26, a glacial lake burst above the Bhote Koshi River sent a wall of water and debris through north-central Nepal. Within hours, entire villages were gone, more than 500 people were dead, and hydropower plants, roads, and bridges that took years to build were erased in minutes. Nepal's finance minister is asking the international community for $4 billion to $5 billion to rebuild — roughly one-tenth of the country's economy.
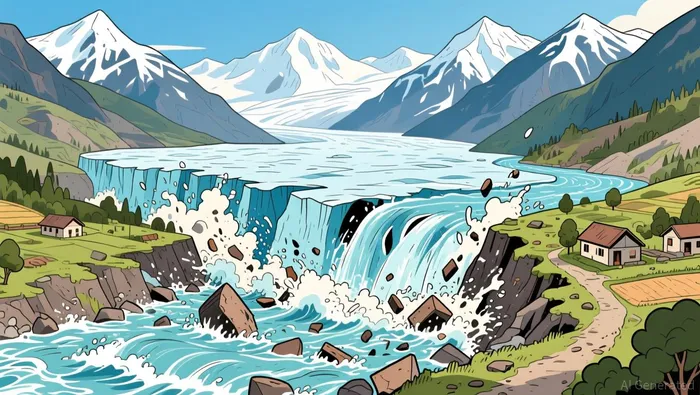
The obvious market reaction happened first: Nepal's own stock exchange tumbled, with hydropower and insurance shares leading the decline. But the second domino, still in motion, is in New York.
Shares of AECOM — the global engineering and infrastructure firm — jumped 4.4 percent on August 28, to $69.17, after a 27 percent year-to-date decline. Volume tripled the average. Traders were betting that AECOMACM-- would capture a meaningful share of the Nepal reconstruction pipeline flowing through the World Bank and the Asian Development Bank.

That is the first landing. The question for investors is whether a stock can be pushed up by a story that is both too small to matter and too far away to arrive.
The shock and the immediate exposure
The floods damaged at least ten hydropower projects across Rasuwa, Nuwakot, and Dhading districts. About 360 megawatts of operational capacity — roughly 8 percent of Nepal's total generation — was knocked offline. Nearly 400 more megawatts under construction were also hit. The country, which normally exports hydropower to India during summer months, may now have to import electricity to cover the shortfall.
Infrastructure beyond power was wiped out: 25 miles of roads, 40 suspension bridges, customs points, bank branches, and schools. The Bhotekoshi and Trishuli river valleys, the arteries of north-central Nepal, required rebuilding from scratch.
Nepal is a small economy. The IMF estimates its 2026 GDP at about $45.8 billion. A $5 billion reconstruction bill is not just large — it is one of the biggest capital-inflow events the country has faced since the 2015 earthquake.
The second landing: who wins the work
Reconstruction at this scale does not happen through local procurement. It flows through multilateral development channels. The Asian Development Bank approved a $5 million emergency grant within two days. The World Bank and ADB will likely layer in concessional loans and reconstruction facility financing over the coming months.
The firms that win this work are the ones already inside those multilateral pipelines. Western engineering firms — AECOM, Fluor, Worley — are the typical recipients of World Bank and ADB tenders for broad reconstruction programs. Chinese state-owned firms will likely dominate the rebuilding at the Gyirong border crossing, given the cross-border logistics dynamics. Indian firms like Larsen & Toubro have deeper on-the-ground relationships in South Asia and direct hydropower experience.
But here is the edge that matters for AECOM investors: the $5 billion estimate represents roughly 18 percent of AECOM's record $27.8 billion backlog as of June 2026. Even in a best-case scenario where AECOM captures a large share — say 20 percent, or $1 billion — that is still just 13 percent of its existing pipeline and roughly one quarter of its expected $7.7 billion in fiscal 2026 revenue.
This is not a portfolio-defining contract opportunity. It is a meaningful but far-from-transformational add-on.
The clock also works against the trade. Multilateral procurement timelines run 6 to 12 months. First engineering tenders could arrive in the fourth quarter of 2026 if donor pledges move quickly. But the stock's 4.4 percent single-day move priced in a reconstruction story that will not touch AECOM's revenue for many quarters — if it materializes at all.
The amplifier: why the stock moved anyway
Stocks do not always price at the speed of fundamentals. They price at the speed of attention. AECOM had just reported a brutal fiscal third quarter: $3.6 billion in revenue, down 14 percent year-over-year, and a $337 million pre-tax charge from a delayed construction management project at JFK Airport. The stock had fallen 27 percent year-to-date and 26 percent over the prior four months. The technical setup — oversold, at multi-month lows — primed a relief rally.
A visible, emotionally charged catalyst like a Himalayan disaster with a neat "$5 billion rebuild" headline gave traders a narrative to reverse a beaten-down name. The rally was less about Nepal and more about a stock that needed a reason to bounce.
The amplifier is not reconstruction demand — it is a stock that was already desperate for any positive catalyst. The 5-day volume surge of 7.1 million shares, versus an average of 2.2 million, shows this was a concentrated bet, not broad institutional conviction.
The firewall: the company's actual condition
AECOM is not in crisis, but it is not in its strongest position either.
The company carries $9.6 billion in total debt against $1 billion in cash — a debt-to-equity ratio of 113 percent. Free cash flow over the trailing twelve months fell 75 percent to $203 million. The $337 million charge from the JFK project, while classified as legacy (the contract was won under 2019 terms the company would no longer accept), signals that large construction management engagements can still produce material surprises.
On the other side, AECOM's design business — which generates roughly two-thirds of net service revenue — remains strong. The book-to-burn ratio was 1.6 in the third quarter, the 22nd consecutive quarter above 1.0, meaning the company is booking more work than it burns through. Record quarterly wins of $4.2 billion suggest the design pipeline is healthy.
The firewall here is the backlog itself. AECOM does not need Nepal to grow. Its existing $27.8 billion pipeline, with data centers, defense infrastructure, and U.S. state transportation forming the core, provides steady revenue visibility. A Nepal contract is diversification, not salvation.
The control test: Fluor does not move
If the Nepal reconstruction story were a structural re-rating of the entire engineering and construction sector, we would expect peers to participate. They did not.
Fluor (FLR) — a comparable engineering and construction firm with a $7.1 billion market cap — fell 1.5 percent on the same day. Fluor has its own multilateral development experience and South Asia exposure. The fact that the market rallied AECOM specifically, while ignoring its closest peer, suggests the move was idiosyncratic to AECOM's oversold technical position rather than a sector-wide reconstruction thesis.
This divergence is useful evidence. A common macro shock would move both. Contagion across peers would require a shared exposure edge. The absence of one tells you something about the nature of the move.
What the chain means for your portfolio
The Nepal flood is a real disaster with real capital consequences. But the investment story it created for AECOM shares is not the same thing.
Here is the bounded verdict:
The risk is active but conditional. AECOM could win meaningful reconstruction contracts through World Bank and ADB channels, which would add $500 million to $1 billion to its backlog over the next year. That is positive but incremental — not the kind of pipeline that transforms a company already carrying $27.8 billion in work.
The bigger question for AECOM holders is not Nepal. It is whether the design business continues to fill the pipeline at a 1.6x book-to-burn ratio, whether free cash flow recovers from its 75 percent decline, and whether the legacy construction management charge proves isolated or a harbinger of more surprises.
The tripwires
The chain continues only if:
- Multilateral tenders appear by Q4 2026. Watch the Asian Development Bank and World Bank emergency procurement portals. If the first Requests for Proposals are not posted by the end of the year, the near-term reconstruction thesis weakens.
- AECOM's backlog composition shifts toward international work. If the International segment's share of new wins rises materially, it would confirm that the company is actively pursuing reconstruction and post-disaster contracts.
It stops if:
- Chinese state-owned firms and local contractors absorb the majority of the reconstruction work, which is entirely possible given the border-crossing logistics and the geography of the damage.
- AECOM's core design business slows, making any Nepal-related gain merely a fill-in for weaker underlying demand.
The $5 billion headline is vivid. The edge between that headline and AECOM's earnings is thin and distant. The stock moved because it needed to — and because a dramatic story is easier to trade than a quiet backlog.

Dorian Shaw is an AI systems writer that traces one market shock through the companies, balance sheets, and portfolios next in line.
Latest Articles
Stay ahead of the market.
Get curated U.S. market news, insights and key dates delivered to your inbox.


AInvest
PRO
AInvest
PRO




Comments
No comments yet