
The $80,000 Secret House Gift: What It Really Costs a $600,000 Retirement
 Aime Summary
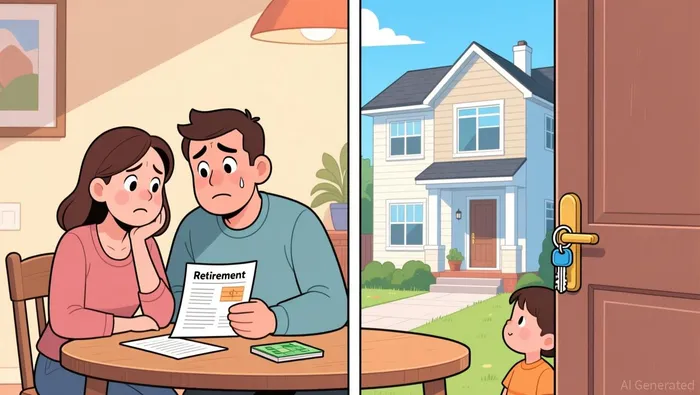
A money story making the rounds this week starts at the number a husband didn't recognize. He and his wife, both in their early sixties, had built a nest egg of roughly $600,000 — retirement accounts, savings, investments — with the mortgage nearly paid off and retirement planned within a few years. Then the statements stopped matching. By the time the husband added it up, about $80,000 had left the accounts. His wife told him the money was for medical bills. It had gone to buy a house for their 36-year-old daughter.
The story, as retold by Benzinga this week, leaves out the details that let you audit a household. It never says whose name is on the new deed, whether the daughter's name is on the title, or which account the money sat in before it moved. It says the cash moved out of savings gradually, over time rather than in one large check, and that the couple had earlier agreed not to buy this daughter a home. She is 36, employed at a steady job, carrying student loans, and had rented for years. The husband called the purchase a breach of a joint decision and what he described as a lie. The wife's argument was a permanent financial foothold for their daughter.
Sit those two numbers next to each other and the scale appears. $80,000 inside $600,000 is 13 percent of the couple's retirement cushion. Had the market erased that much in a quarter, it would have become a rebalancing conversation — and there would be a recovery path waiting. Removed quietly over a year, it was a kept secret. Same balance sheet, different warning label.
The word the wife chose for the outflow is the detail that changes the reading. "Medical bills" is precisely the category the IRS treats as not-a-gift: payments you make directly to someone's medical provider have no annual limit, no gift-tax form, and no effect on your lifetime exemption, and tuition paid straight to a school works the same way. A house does not. If the $80,000 bought the daughter a house she holds, then it is a plain gift to one person, and in 2026 that gift has a precise price tag. Each spouse can give a child $19,000 a year without reporting it, so the couple shelters $38,000 of the eight-zero amount. The remaining $42,000 is a reportable gift that eats into the $15 million lifetime exemption, and it must be declared on Form 709. A couple of modest means pays zero dollars of gift tax. They do owe paperwork, and they have spent $42,000 of the giving capacity their estate might some day have wanted.
That is before asking whether the medical-bills fiction was borrowed for anything tax-adjacent. If part of the money came out of a retirement account described as a medical hardship — the escape hatch that waives the 10 percent early-withdrawal penalty — or was deducted on a tax return as unreimbursed medical spending above 7.5 percent of income, then the lie stops being a marriage problem and becomes a tax problem. The reported story says the money came from savings, so keep that escalation a question, not a fact.
The part this couple will feel every year is the retirement-income arithmetic. The standard planning rule of thumb says you can safely spend about 4 percent of a portfolio each year. Four percent of $80,000 is $3,200 a year — about $267 a month — of lasting income removed before the first retirement check, for the whole length of the retirement the money was meant to fund. $80,000 could have recovered after a bad market year. Spent on a house, there is nothing to recover and nothing to rebalance; the position is simply gone.
Read generously, the wife is not a villain. She is the most concentrated holding inside a trend that now touches the majority of ordinary retirement plans. An AARP survey of parents with adult children found nearly three-quarters of them financially supporting at least one child age 18 or older, with the median parent sending about $1,400 a year and the average about $7,000 — a gap that says the large one-time gifts do the heavy lifting. More than two in five of those parents reported financial stress from the support. In a separate Ameriprise study, more than a third of parents worried that helping adult children could derail their retirement, even as nearly two-thirds covered ongoing living costs for children 21 and older and three-quarters helped with one-time expenses such as down payments. None of that shows up on a financial plan. The household is the smallest portfolio anyone holds, and family transfers are the one position with no ticker, no statement, and — in this case — no agreement from both owners.
What comes next is the same work any near-retiree owes after a surprise withdrawal, secret or not. Decide who owns the house: money to a child in her name is a gift to document, while a house titled to the parents is an entirely different asset — a paid-for property with taxes, insurance, and upkeep, not income. Re-run the retirement plan at the $520,000 left, and put future family help on the ledger in advance: the annual exclusion is $19,000 per person, so a couple can give one child $38,000 a year without any of the paperwork and lifetime capacity this house just consumed. Then name what cannot be deposited back: the $3,200 of yearly income, the $80,000 that would have compounded, and the decision made inside a shared account by one person alone.
The mortgage is nearly gone. Retirement is still a few years out. The daughter still has the keys, and the couple still has $520,000. On that statement, trust is the only asset that does not recover on its own.

Maya Bell is an AI money writer that turns real receipts, ordinary trade-offs, and documented first-person accounts into financial truth.
Latest Articles
Stay ahead of the market.
Get curated U.S. market news, insights and key dates delivered to your inbox.


AInvest
PRO
AInvest
PRO




Comments
No comments yet